PSP Investments Agrees to Buy 50% of Enercare for C$1.6 Billion, Calling It Among Its Most Significant Direct Infrastructure Investments in Canada
PSP Investments will buy 50% of Enercare for C$1.6 billion, a deal it says ranks among its most significant direct infrastructure investments in Canada. Close is expected in the first half of 2027.
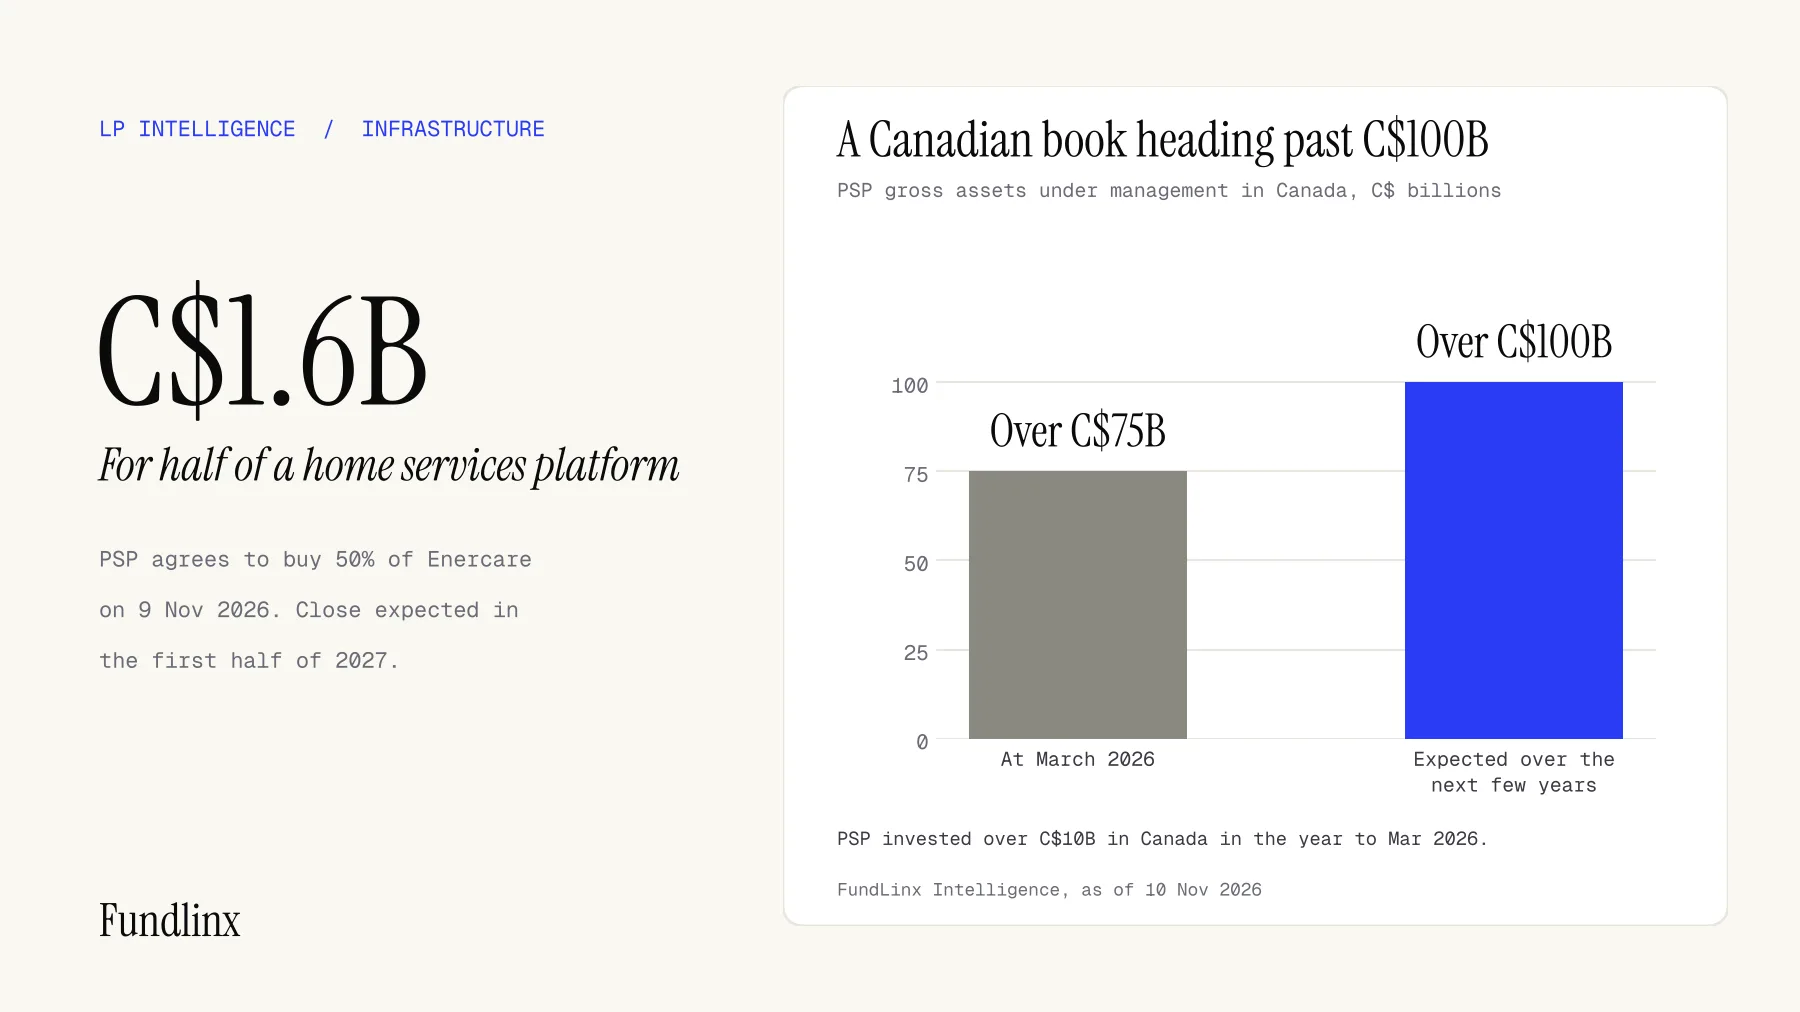
The Public Sector Pension Investment Board, known as PSP Investments, announced on 9 November 2026 that it has signed an agreement to acquire a 50% interest in Enercare Inc. for C$1.6 billion. The sellers are Brookfield and its institutional partners, and the transaction is expected to close in the first half of 2027 once customary regulatory approvals are received. Enercare provides water heaters, heating, ventilation and air conditioning equipment, water purification systems and protection plans to more than 1.4 million Canadian homes and businesses. For fund managers who sell infrastructure strategies to a pension fund, the deal shows where a Canadian pension investor with more than C$75 billion of gross assets in the country wants to put capital at home, and how it prefers to do it.
What PSP announced
PSP will hold the investment in its High Inflation Correlated Infrastructure portfolio. Andrew Alley, Managing Director and Global Head of Infrastructure Investments at PSP, said it will rank among the fund's most significant direct infrastructure investments in Canada. He pointed to Enercare's customer relationships, recurring revenue model and market position as the reasons it fits an infrastructure mandate. Enercare has a strong presence in Ontario and Quebec and a growing footprint in Western Canada, and it will continue to be led by its existing management team, with Nick Perreten as President and Chief Executive Officer. The company also runs a program called Enercare Advantage, which the announcement describes as giving customers an affordable and reliable option when they make equipment decisions. The announcement says both partners remain committed to the company's long-term growth. It does not state who will hold the other 50% after closing, so we do not speculate on that point. All figures are in Canadian dollars.
The numbers behind the deal
The C$1.6 billion price is for half of the company. PSP also put the deal in the context of its Canadian book: in the fiscal year ended March 2026 it invested more than C$10 billion in Canada, which brought its gross assets under management in the country to over C$75 billion. It expects its Canadian investments to surpass C$100 billion over the next few years. Both figures are stated as minimums, so the gap is at least about C$25 billion of additional gross assets, or roughly a third more than today, our arithmetic from the two figures. On that basis, the Enercare price is about 6.4% of the growth PSP says it expects, again our arithmetic. PSP has been an investor in Enercare since 2018, when it co-invested alongside Brookfield in the privatization of the company, and the company has since expanded into Quebec and Western Canada.
How it compares
This is the fourth PSP transaction we have covered since 22 October, counting the US$790 million shopping center venture with Nuveen Real Estate, the US office account in which PSP led a Bouwinvest and Tishman Speyer partnership, and the Blackstone-led deal for 49.9% of a Mitsubishi LNG Canada holding company alongside three other Canadian pensions. In each case PSP appears next to a named operating or sponsor partner rather than writing a blind commitment to a fund. Enercare follows the same pattern, with the added feature that the partner, Brookfield, is already a co-owner. Our reading is that PSP's deal flow this autumn is weighted toward partnerships and direct stakes, though we have no verified figure for how its fund commitments compare.
The named LP
PSP Investments is a Canadian pension investor, part of the Canadian pension fund universe, and it describes a long-standing relationship with Brookfield in which the two have invested together across multiple infrastructure sectors and geographies. The announcement gives its Canadian gross assets, its recent annual Canadian investment pace and the portfolio sleeve that will hold Enercare. We have no verified figures for its typical ticket size in funds or for whether it backs first-time managers, so we offer none.
What a GP should do
This section is our advice, not guidance from PSP. First, if you run an infrastructure strategy, describe your assets in the terms PSP used here: customer relationships, recurring revenue and market position. Second, expect PSP's Canadian infrastructure appetite to show up in direct and partnership deals, so a co-investment sleeve or a partnership structure alongside your fund may fit better than a fund-only pitch. Third, avoid approaching the infrastructure team about Canadian home services or similar assets until the transaction closes, because its attention is likely to sit with the deal until then. Fourth, map who in your network has worked with PSP and Brookfield on earlier deals, using our piece on mapping warm paths through a long-running sponsor partnership as the method.
What to watch next
Watch for regulatory approvals and the first-half 2027 closing, which falls within roughly eight months of the announcement at the outside, our arithmetic, and for whether PSP's Canadian assets move toward the C$100 billion mark it describes. A further partnership deal in Canadian infrastructure would suggest the pace we have seen since October is a pattern rather than a run of coincidences. FundLinx members can see which Canadian and global pensions are active in infrastructure.
FundLinx Intelligence | FundLinx.ai
Playbooks, LP moves and compliance notes for emerging managers. Unsubscribe any time.