CPP Investments, OMERS, IMCO and PSP Join Blackstone in a $3.1 Billion Deal for 49.9% of a Mitsubishi LNG Canada Holding Company
Four of Canada's largest pension investors joined Blackstone in a $3.1 billion deal for 49.9% of a Mitsubishi subsidiary that holds its stake in LNG Canada. Mitsubishi stays in control.
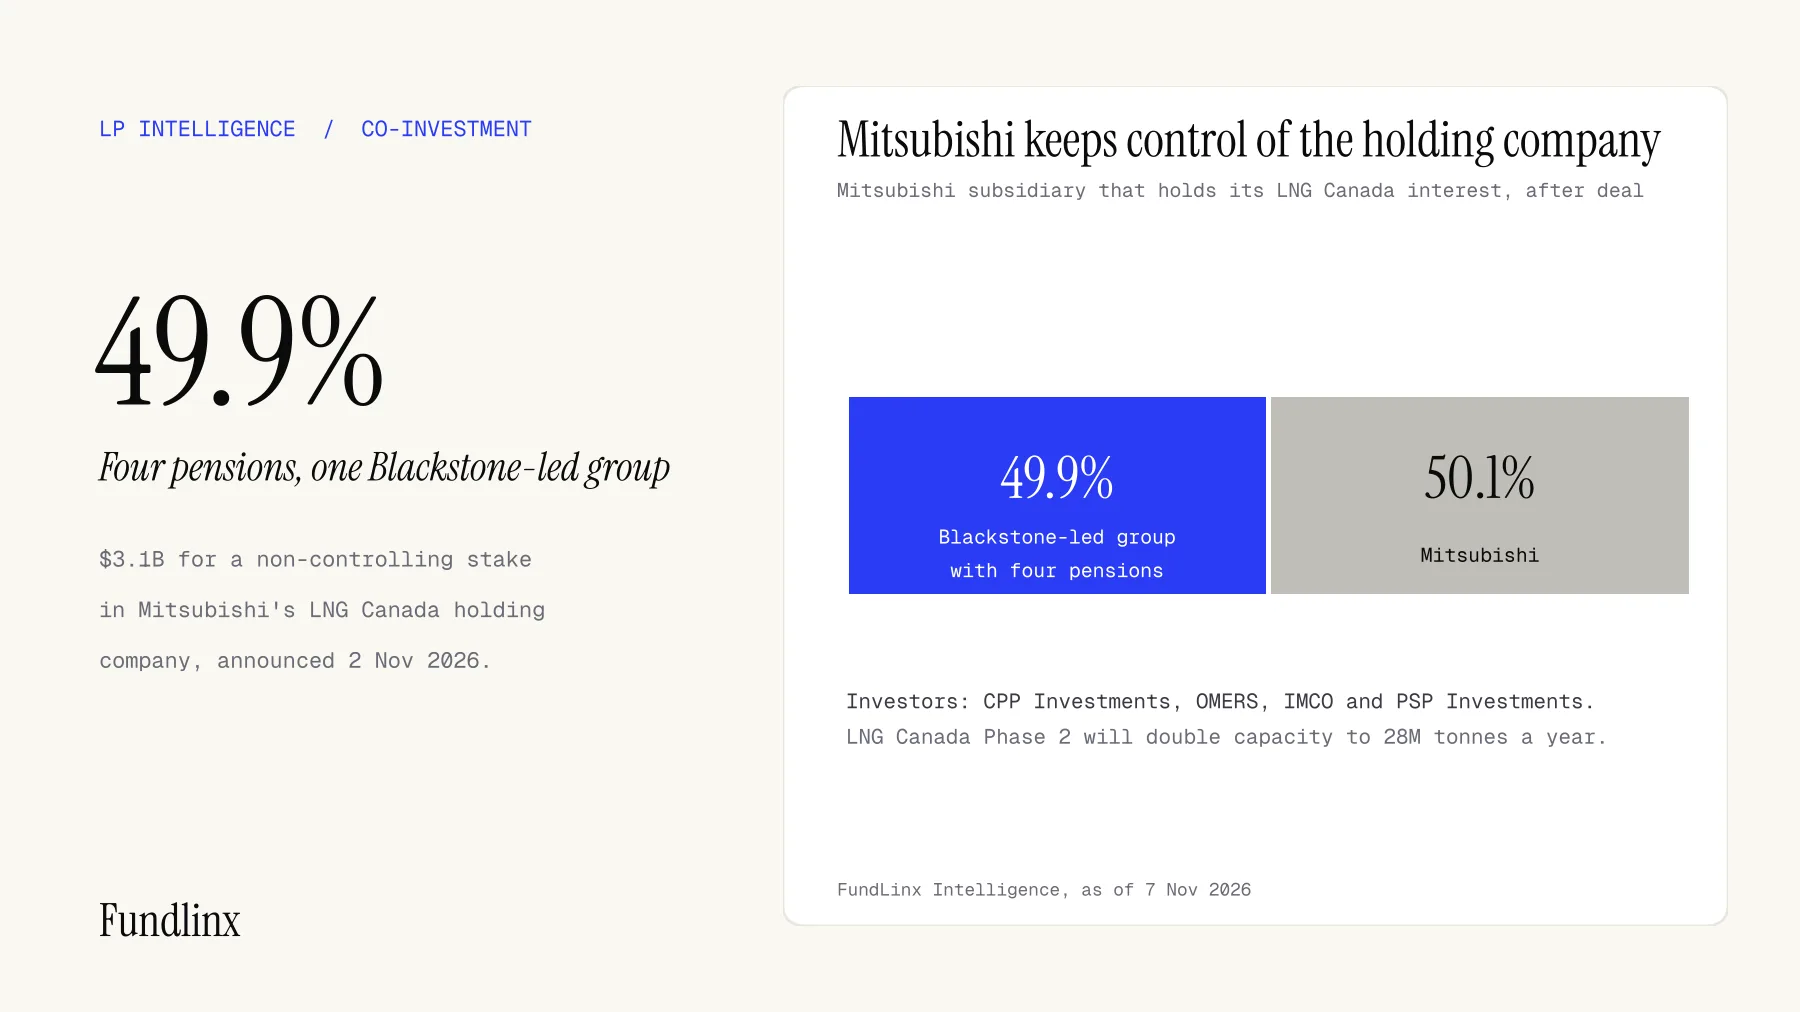
On 2 November 2026 Blackstone announced that funds managed by Blackstone Credit & Insurance, together with four Canadian institutional investors, have agreed to invest $3.1 billion to acquire a 49.9% non-controlling interest in a Mitsubishi Corporation subsidiary. That subsidiary holds Mitsubishi's interest in LNG Canada. The investor group includes CPP Investments, through wholly owned subsidiaries of CPPIB Credit Investments Inc., OMERS, the Investment Management Corporation of Ontario (IMCO) and PSP Investments. It is unusual to see four of Canada's largest pension funds named in a single announcement beside one manager, and it tells GPs a good deal about how these investors now prefer to deploy capital at scale.
What was announced
LNG Canada is described in the announcement as Canada's first and only large-scale liquefied natural gas export terminal. Once its Phase 2 expansion is complete it will double the facility's production capacity to 28 million tonnes per annum, which would make it one of the largest LNG facilities in the world. The Mitsubishi subsidiary in the deal holds a 15% interest in the terminal, so a 49.9% stake in that subsidiary gives the group an indirect economic interest of roughly 7.5% of LNG Canada. That 7.5% is our arithmetic from the two disclosed percentages, not a figure from the parties. Mitsubishi remains the controlling partner and keeps its full share of the terminal's output.
Rick Campbell, Senior Managing Director at Blackstone Credit & Insurance, framed Blackstone as a financial partner to Mitsubishi, a company with more than 50 years of experience across the LNG value chain. Geoff Souter, Managing Director and Head of Real Assets Credit at CPP Investments, called LNG Canada a high-quality, globally strategic asset with strong long-term fundamentals and attractive return potential for the CPP Fund, and said the deal lets CPP Investments invest at scale in Canada alongside Mitsubishi.
The numbers
The headline figures are $3.1 billion for 49.9%. The announcement does not say how the $3.1 billion divides between Blackstone's funds and the four pensions, so we cannot give any one investor's ticket and the individual amounts are undisclosed. What can be counted is the shape of the group: of the five named investor groups, four are pension investors, or 80% by count. The share of capital they supplied is not disclosed, so we draw no conclusion about who holds most of the stake. On the other side, Mitsubishi keeps the remaining 50.1% of the subsidiary, which is why the deal is better described as a minority investment into an existing owner than as a sale of the asset.
How it compares
This is the third large transaction involving these names in roughly ten days. We covered the agreed sale by CPP Investments and OMERS of their 63.9% of Associated British Ports on 23 October, and OMERS taking an indirect minority stake in La Trobe Financial on 28 October. The pattern across the three is consistent: large Canadian pensions selling mature holdings, then buying minority positions alongside a lead partner, rather than only writing fund commitments.
The named LPs
The four investors are all Canadian public-sector pension institutions, and the announcement gives no assets under management, target allocations or earlier ticket sizes for any of them, so we offer none here. It does give one useful clue about where the decision sat at CPP Investments: Souter's title places the deal with its real assets credit team. That is our reading of a job title, not a statement about how any of the four decided. The announcement says nothing about whether any of them backs first-time managers, so no Fund I or Fund II conclusion should be drawn from it. A GP can still map the group by region on our list of Canadian pension investors.
What a GP should do
This section is our advice, not guidance from any of the parties. First, treat a lead manager with a large balance sheet as a route to several pensions at once: here a single partner assembled four. Second, if you run real assets credit or infrastructure strategies, prepare a structure that can take a minority position in a corporate holding vehicle, because that is what was bought. Third, ask yourself whether your co-investment offer can be sized for tickets of this scale. Fourth, expect these pensions to be well known to each other, so a reference from one is likely to be heard by the others. Fifth, lead any approach with the asset-level case, since the CPP Investments quote stresses asset quality and long-term fundamentals before anything else. For the relationship-mapping side of this story, see our companion piece on mapping warm paths between the four pensions.
What to watch next
Watch for the completion of the transaction and for any disclosure of how the capital is split between the investors. Also watch whether further Canadian pension co-investments follow in energy infrastructure now that Phase 2 of LNG Canada is moving toward completion. FundLinx members can see which pensions are allocating to infrastructure.
FundLinx Intelligence | FundLinx.ai
Playbooks, LP moves and compliance notes for emerging managers. Unsubscribe any time.