Virginia Retirement System Commits €125 Million to Igneo's European Infrastructure Fund IV, About 2.1% of a Fund That Closed at Its €6 Billion Hard Cap
Virginia's pension committed €125 million to Igneo's fourth European infrastructure fund, which closed at its €6 billion hard cap, 50% above its €4 billion target, in six months.
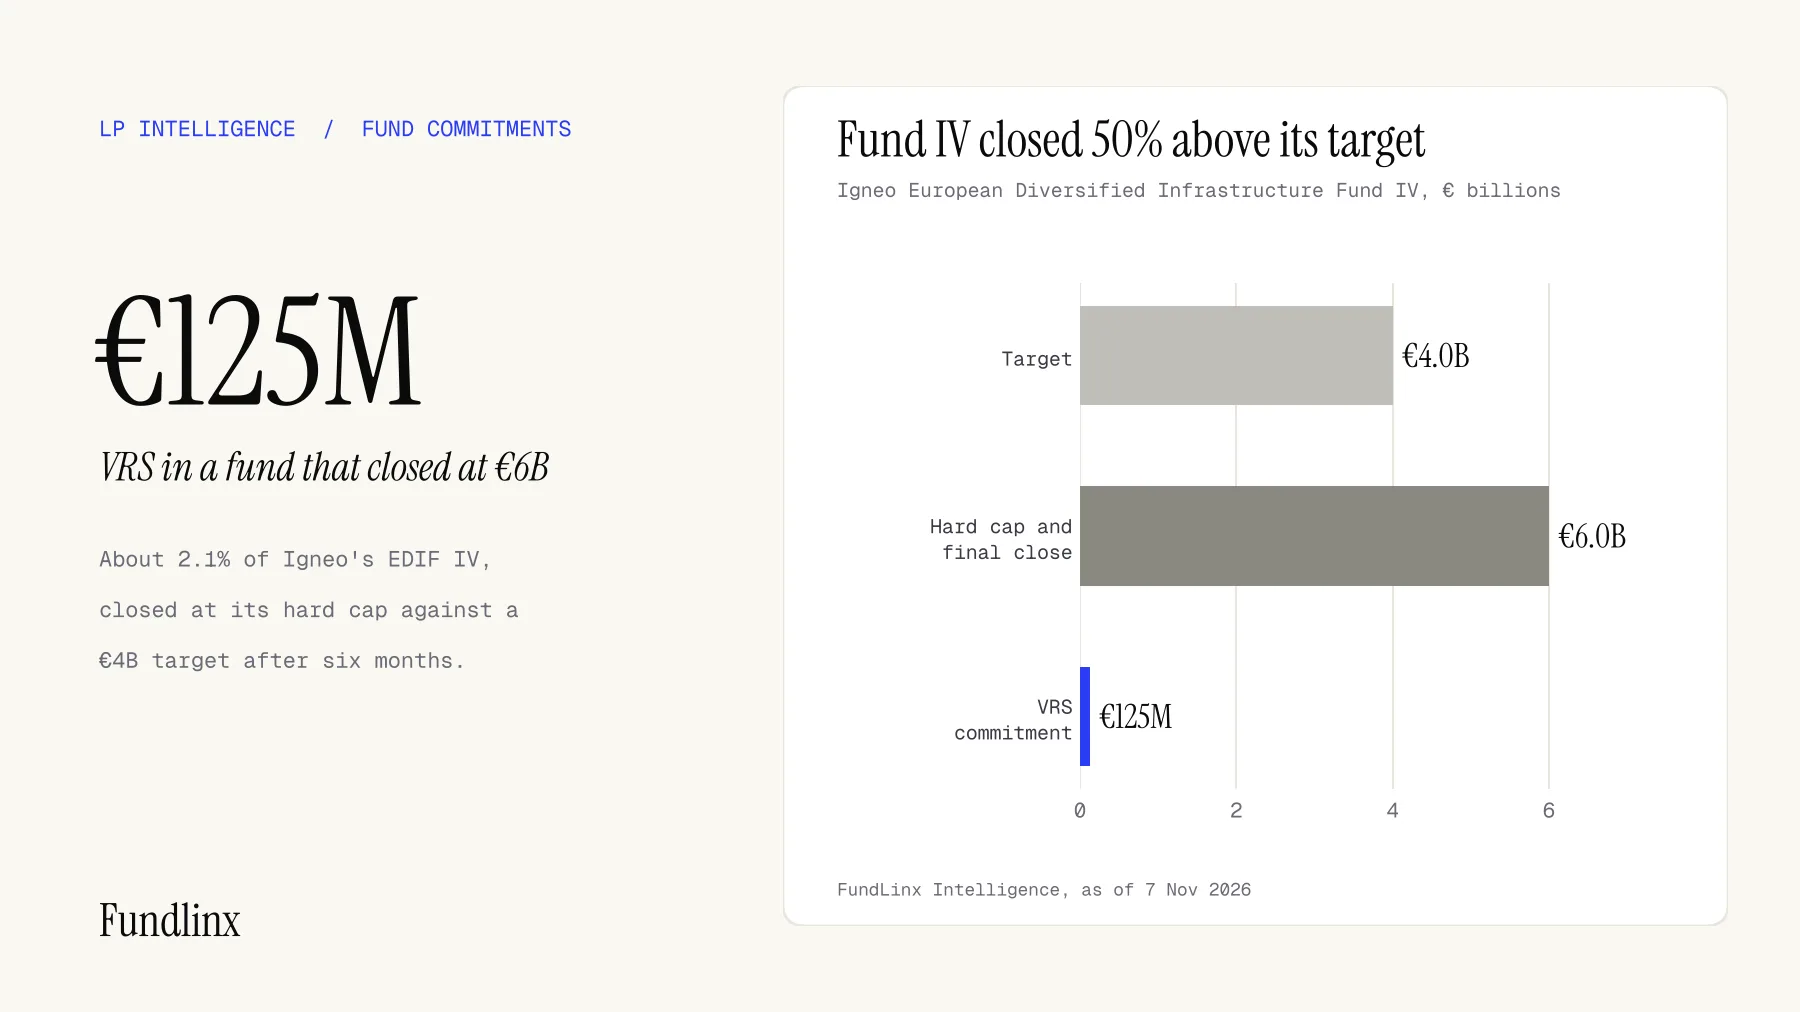
The Virginia Retirement System (VRS) has committed €125 million, about $139.6 million, to Igneo European Diversified Infrastructure Fund IV (EDIF IV). Igneo Infrastructure Partners announced on 3 November 2026 that the fund held its final close at its €6 billion hard cap, against a target of €4 billion, and that VRS is among the backers. The fund reached that size only six months after launch. For infrastructure managers raising capital in Europe, the numbers say as much about demand for mid-market core and core-plus strategies as about any one investor.
What was announced
EDIF IV is a closed-end commingled fund focused on core and core-plus middle-market infrastructure assets in Europe. Igneo said it secured commitments from more than 90 institutional investors across Europe, Asia-Pacific and North America, and that the investor base includes pension funds, insurers, sovereign investors and family offices. The fund made its first investment in September 2026, acquiring Neumann Group, a German incinerator bottom ash recycling business. Hamish Lea-Wilson, partner and head of Igneo Infrastructure Partners Europe, said demand would have supported a much larger fund but that the firm chose to stay in the part of the market where its team has deep experience. Carolyn Gilchrist, partner and global head of capital formation, said the fund drew extensive support from existing investors and added new relationships across the three regions.
The numbers
The €6 billion close is 50% above the €4 billion target. VRS's €125 million is about 2.1% of the fund, which is our arithmetic from the two disclosed figures. If the capital had been spread evenly across the more than 90 investors, the average commitment would have been under €67 million, so VRS sits at nearly twice that level. The actual spread of commitments is undisclosed, and we treat the average only as a rough yardstick. By count, the fund drew investors from three regions and four investor types, which is the breadth a manager wants in a fund of this size.
How it compares
This is not VRS's first large private-markets move in recent weeks. We reported that the Virginia Retirement System committed $675 million to private equity and credit in four weeks, and that two US pensions backed Spectrum Equity XI within 12 days. The new commitment is different in one respect: it is a euro-denominated European infrastructure fund rather than a US private equity or credit vehicle. Across the quarter, the wider infrastructure market has been busy at the top, and we looked at how three mega funds closed more than $42 billion of infrastructure capital in the third quarter. EDIF IV sits in the middle market rather than among those very large funds.
The named LP
VRS is a US public pension fund. Its total assets are quoted at slightly different figures in different places, so we do not give one here. The commitment is a single data point about its appetite for European core and core-plus exposure, and we do not know its target allocation to infrastructure, whether it plans further European commitments, or whether it backs first-time managers. Igneo is an established manager running its fourth fund in this strategy, so the commitment says nothing about emerging manager appetite.
The scale matters too. A €6 billion fund is large for a strategy that targets the middle market, and the manager said it chose to stop there even though demand could have supported more. For an LP, that matters because commitments of this size compete for the same limited number of assets, and a manager that holds its size is making a promise about where it will invest. VRS has not disclosed, in anything we have seen, how it weighs fund size when it commits. We therefore treat the €125 million as evidence of interest in the strategy, not of a policy.
What a GP should do
This section is our advice, not guidance from VRS or Igneo. First, if you raise for European mid-market infrastructure, expect US public pensions to be in the room, and prepare materials in euros with currency-hedging options clearly set out. Second, note how the close was framed: the manager emphasised staying disciplined on size, and a stated discipline on fund size is something LPs may value. Third, show a first investment early. EDIF IV had one asset, in a niche recycling business, by the time it closed, which gives LPs something concrete to diligence. Fourth, plan your final close timetable around the board calendars of US pensions, since commitments of this kind are approved in meetings that follow a fixed schedule. Fifth, if you are a smaller manager, read the six-month, oversubscribed close as a sign that capital is flowing to proven platforms, and consider emphasising a niche where a large fund would not compete.
What to watch next
Watch for further commitments to EDIF IV to be disclosed by other public investors, and for Igneo's next acquisitions as it deploys the fund. FundLinx members can see which pensions are allocating to European infrastructure.
FundLinx Intelligence | FundLinx.ai
Playbooks, LP moves and compliance notes for emerging managers. Unsubscribe any time.