Virginia Retirement System Commits $675 Million to Private Equity and Credit in Four Weeks, Including $145 Million for Spectrum Equity XI
VRS closed six commitments worth $1.325 billion in four weeks, with $675 million going to private equity and credit, about a third of the private markets capital in the prior window.
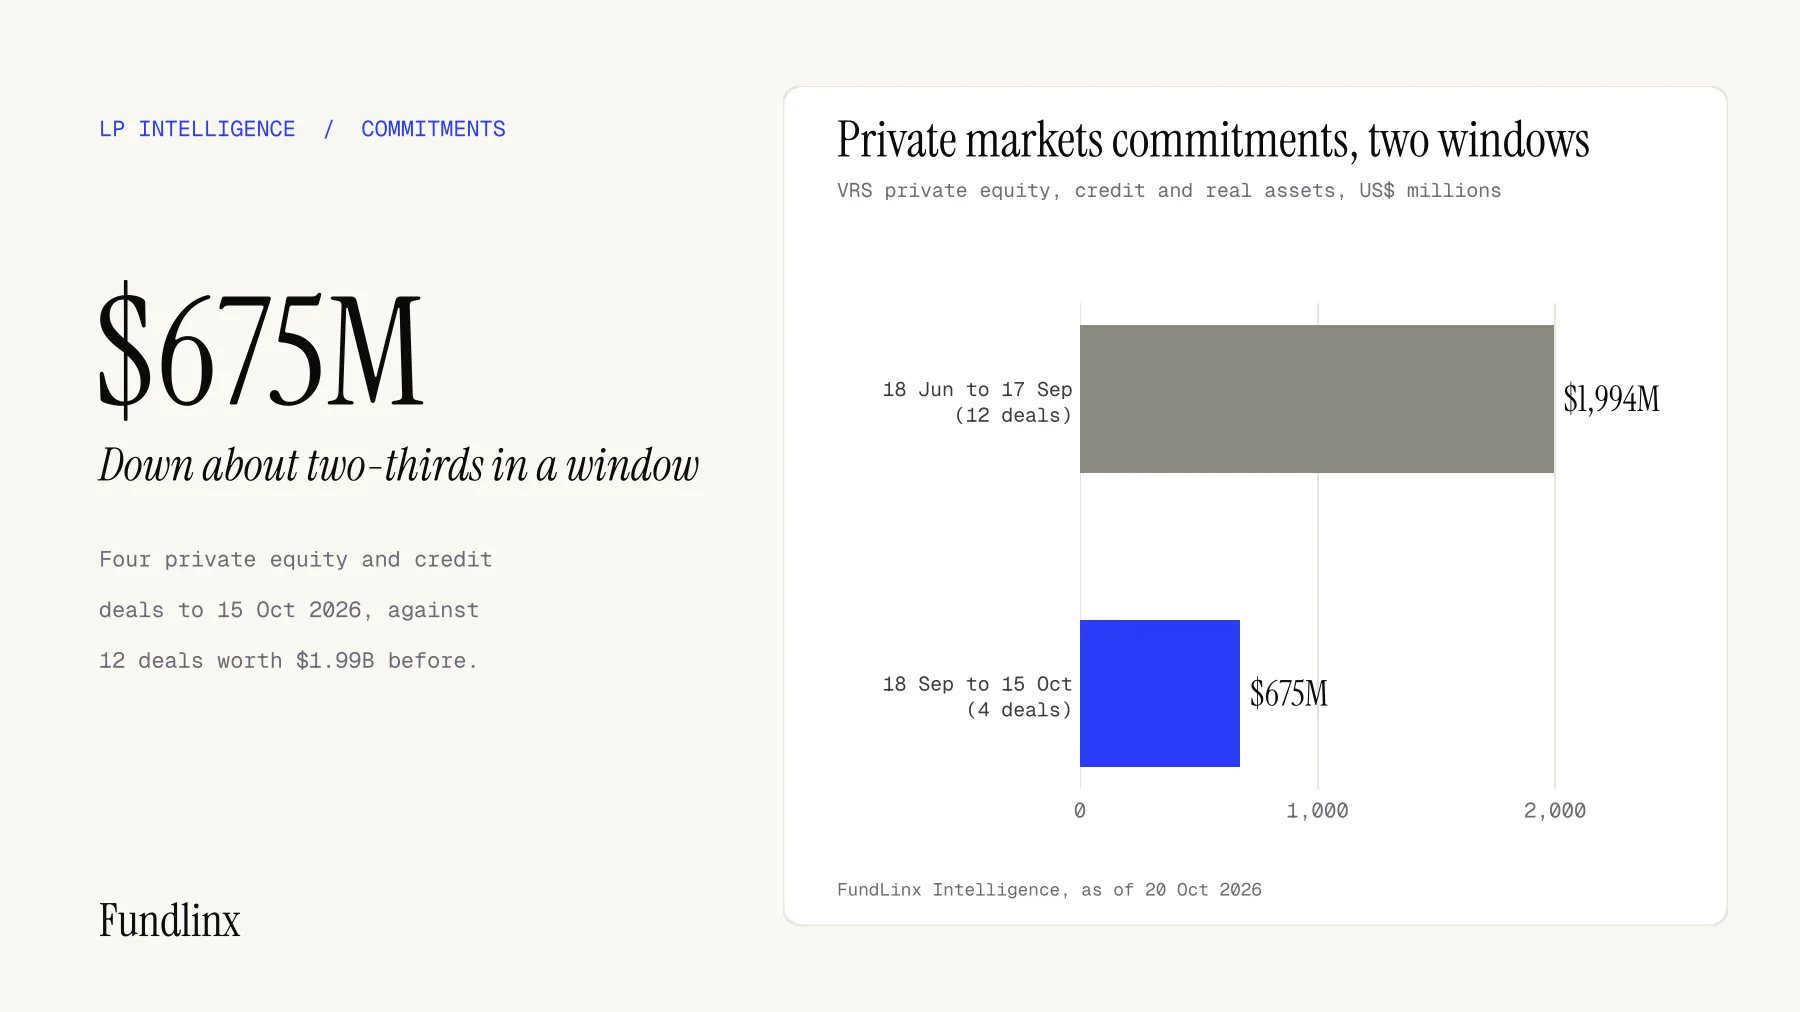
The Virginia Retirement System booked six new commitments worth $1.325 billion in the four weeks to 15 October 2026, and four of them, worth $675 million, went to private equity and private credit. The largest private markets tickets were $300 million to Castlelake Asset-Based Private Credit IV, $200 million to Audax PE VIII and $145 million to Spectrum Equity XI. The other two commitments were $250 million to a public equity manager, Atalan Capital, and $400 million to JP Morgan Hybrid Growth in the pension's exposure management portfolio.
What the pension committed to
Private equity took three tickets: $200 million to Audax PE VIII with a five-year funding period, $30 million to Monomoy Family Fund with six years, and $145 million to Spectrum Equity XI, also six years. Credit strategies took one: $300 million to Castlelake Asset-Based Private Credit IV, funded over three years. The effective dates run from 3 September to 1 October. The recap covers 18 September to 15 October, so the first two private equity dates fall slightly before the window opens.
Measured by capital, private equity took $375 million, or 28% of the $1.325 billion, credit took $300 million (23%), exposure management took $400 million (30%) and public equity took $250 million (19%). By count, private equity accounted for three of the six commitments (50%) and each of the other three programs for one (17%). Private equity and credit together are $675 million, about 51% of the capital and four of six, or 67%, of the commitments.
How it compares with the previous window
The pension's previous recap, covering 18 June to 17 September, listed 13 commitments worth about $2.02 billion, and 12 of them, worth about $1.99 billion, were in private markets across real assets, private equity and credit. On that basis private markets capital fell about 66% between the two windows, and the count fell from 12 deals to four. Private equity alone went from five tickets totaling $976 million, an average of about $195 million, to three tickets totaling $375 million, an average of about $125 million. The earlier window included $300 million to GTCR XV and $200 million each to Apollo Investment Fund XI and General Atlantic SMA II. No ticket in the latest window was above $200 million, and none went to real assets.
The LP behind the tickets
VRS is a US state pension fund with a total fund value of about $136.3 billion at 31 August 2026. Andrew Junkin is its chief investment officer. Its August allocation report showed private equity at 14.2% of the fund against a 16.0% policy weight, credit strategies at 14.3% against 16.0%, and real assets at 13.2% against 14.0%. A later daily allocation report lists a different private equity policy weight of 15.0%, so the gap may be narrower than August suggests. On the August figures, a 1.8 point private equity gap on $136.3 billion is roughly $2.5 billion, our arithmetic. The funding periods on the private markets tickets, three to six years, show the pension paces its commitments rather than writing one-off checks.
Spectrum Equity is a name our readers will recognise from our note on its Fund XI close at $2.5 billion. VRS is not the only US public pension in the vehicle: the Texas County and District Retirement System also closed $100 million to a Spectrum Equity XI vehicle on 30 September. Both are part of a wider pattern of large US public pension commitments, as seen in Maine PERS lining up up to $100 million for AE Industrial Partners Fund IV.
What GPs should do now
This is our advice, not something the pension has said. A manager raising a flagship buyout or growth equity fund should note that VRS tickets in its last two windows ran from $30 million to $300 million, with a median of about $200 million across eight private equity commitments. A fund that can absorb that size, and that fits a five- or six-year funding period, is the realistic profile. Credit managers should note the pension's appetite for asset-based and hybrid credit, with $300 million to Castlelake in this window and $150 million to $300 million tickets in the last one.
Because the August report showed private equity and credit below policy weights, lead with where your strategy fits the sleeve, not with a generic track record. Expect the commitments to surface in the pension's next investment recap, since trustee meetings are scheduled for November and December. Other US state pensions tend to be most receptive when a manager arrives with a clear funding timeline and a reference from a manager they already back.
What to watch next
Watch whether the November recap shows private markets activity returning toward the earlier window's pace, and whether the private equity policy weight is confirmed at 16.0% or 15.0%. FundLinx members can see which pensions are writing private equity tickets this quarter.
FundLinx Intelligence | FundLinx.ai
Playbooks, LP moves and compliance notes for emerging managers. Unsubscribe any time.