Maine PERS Lines Up Up to $100 Million for AE Industrial Partners Fund IV After Approving $890 Million of Commitments in September
A $23 billion state pension has up to $100 million for a single sponsor on its 8 October agenda, a month after approving $890 million across four managers. Credit took 56% of the September total.
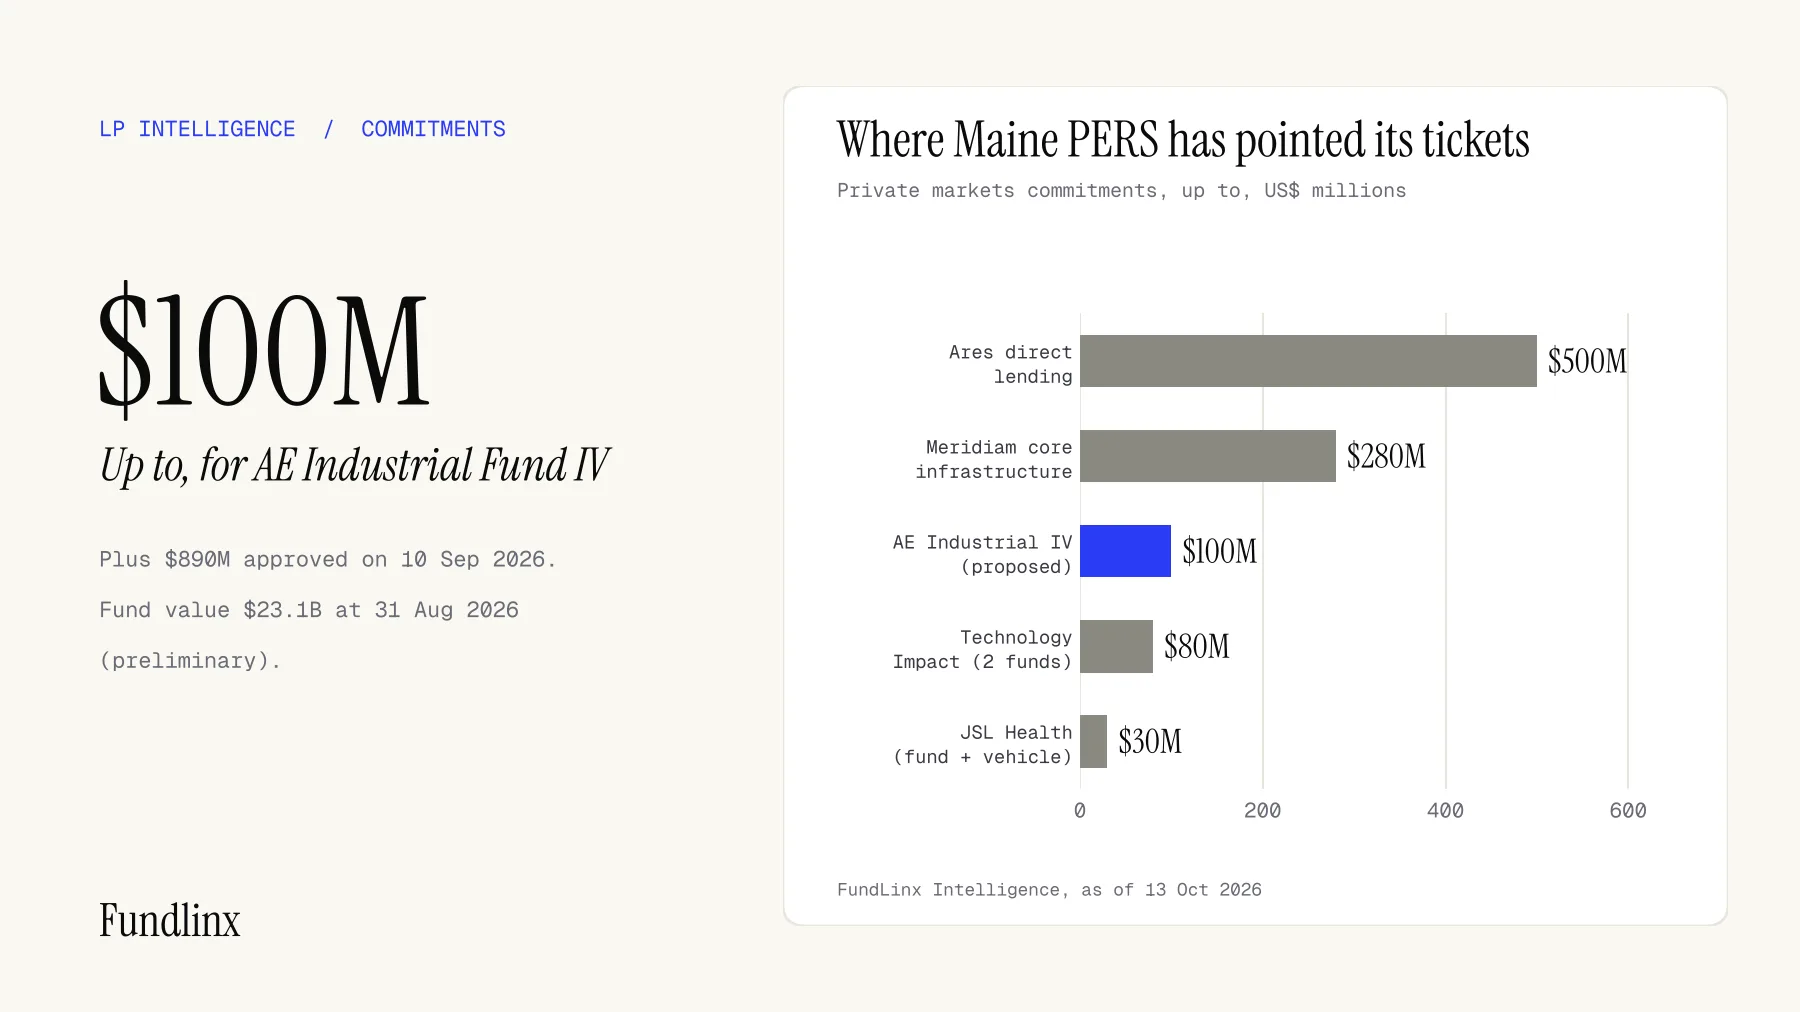
On 10 September 2026, the board of Maine Public Employees Retirement System (MainePERS) approved four private market recommendations worth up to $890 million. Four weeks later its 8 October meeting was due to consider a fifth: up to $50 million for AE Industrial Partners Fund IV and up to $50 million for a separate vehicle that invests in assets owned or being acquired by the fund. We could not confirm the outcome of the October item, because the meeting record had not yet been posted when we checked, so we treat it as a proposal. Together the two steps show how a mid-sized state pension fund spreads its tickets between credit, infrastructure, technology and healthcare.
What the board approved and what is pending
The September approvals were unanimous among the five trustees voting on each item, and all are subject to final due diligence, legal review and negotiation. They were: up to $500 million to Ares Senior Direct Lending Core BYOT Master Fund, with the investment team given discretion over deployment, redemption and timing; up to $280 million to Meridiam North America Core Infrastructure Fund I; up to $40 million each to Technology Impact Fund III and Technology Impact Growth Fund III; and up to $20 million to JSL Health Capital Fund II plus up to $10 million to a separate vehicle investing in that fund's assets. The chief executive, chief investment officer and general counsel were authorised to sign.
AE Industrial Partners Fund IV was presented to MainePERS at a managers meeting in Portland on 22 September. The October proposal carries the same conditions: final due diligence, legal review and negotiation. Staff told the board for each recommendation that they believe it is unlikely to lead to meaningful exposure to fossil fuel or for-profit prison companies, a screen a GP should be ready to speak to.
How the numbers compare
By our arithmetic, the September total of $890 million is about 3.9% of the fund's preliminary market value of $23.1 billion at 31 August 2026, and adding the October proposal brings the total to $990 million, or about 4.3%. By capital, Ares was 56% of the September total, Meridiam 31%, the two Technology Impact funds 9% and JSL 3%. By count, the four approvals covered four managers and six vehicles, and one of the four managers (25%) was a credit manager. The Meridiam commitment is largely a roll: staff proposed moving about $280 million of existing exposure into the new fund, and the pension says it had previously committed $364 million to the Meridiam platform. An earlier proposal had cited $300 million, so the approved figure is lower. Meridiam's North American strategy also featured in our playbook on its continuation vehicle, and a roll like this is the LP-side view of a secondary transaction: the pension keeps its exposure and changes the vehicle.
The LP behind the commitments
MainePERS is a US state pension system. Its defined benefit assets had a market value of $23.39 billion at 30 June 2026, up from $21.41 billion a year earlier, and the fund returned 11.43% on a market basis for the 2026 fiscal year. It was at $23.1 billion at 31 August, with a preliminary 6.0% calendar year-to-date return. James Bennett is Chief Investment Officer and Scott Lupkas is Deputy Chief Investment Officer, and the board works with outside consultants including Cambridge Associates and Albourne, the latter of which concurred with the four September items. The fund already has deep relationships: it says it has committed $516 million to earlier Ares funds, with $268 million of net asset value at 31 March 2026. Nothing in the materials we reviewed says whether it backs first-time managers, and the September tickets went to established sponsors.
What GPs should do now
This section is our advice. First, note the ticket range: from $10 million to $500 million, with infrastructure at $280 million and the October proposal at $50 million plus $50 million. A sponsor with a flagship fund can expect to be assessed against a ticket of $50 million or more, while specialist and smaller vehicles are sized in the $10 million to $40 million range. Second, prepare a short answer on fossil fuel and for-profit prison exposure, since staff address it in every recommendation. Third, offer a companion vehicle where it makes sense: both AE Industrial and JSL came with a separate vehicle investing alongside the main fund, which the board approved for JSL and was due to consider for AE Industrial. Our guide to answering a pension's open manager search covers how to present a package like that. If you run semi-liquid credit, see our playbook on liquidity terms, because the Ares item gave the investment team discretion over redemption timing. Introductions are most likely to come through the investment team and its consultants, and through general partners already in the portfolio.
What to watch next
Watch for the posted record of the 8 October meeting, which will show whether the AE Industrial proposal passed, and for the board's next meeting on 12 November. FundLinx members can see which US state pensions are adding to private markets.
FundLinx Intelligence | FundLinx.ai
Playbooks, LP moves and compliance notes for emerging managers. Unsubscribe any time.