Texas County and District Retirement System Books Its Tenth Direct Lending Commitment of 2026, $250 Million to Crescent, Lifting the Year to $1.975 Billion
TCDRS closed $250 million to Crescent on 2 October, its tenth direct lending commitment of 2026. Direct lending has taken 77% of the $2.6 billion it has committed to credit this year.
The Texas County and District Retirement System closed a $250 million commitment to Crescent (TX) Direct Lending Fund, L.P. on 2 October 2026, its tenth direct lending commitment of the year. The ticket takes 2026 direct lending commitments to $1.975 billion, up from $1.725 billion when we reported its $300 million Silver Point commitment on 30 September. That is nearly double the pension's 2025 direct lending total of about $1.0 billion plus EUR 100 million, as we reported then. The fund's size and terms were not disclosed.
What the pension committed to
Crescent is the third direct lending closing in 30 days. On 3 September TCDRS closed $200 million to TPG Essential Housing IV, on 28 September $300 million to Silver Point Silver Star Holdings, and on 2 October $250 million to Crescent. Those three tickets total $750 million, which is 38% of the year's direct lending capital and three of the ten commitments (30%). The Crescent ticket is 12.7% of the year's capital and 10% of the count, and it sits above the $197.5 million average of the ten. Like the pension's March commitment to TPG Direct Lending, the vehicle name carries a "(TX)" suffix.
Where the credit capital went
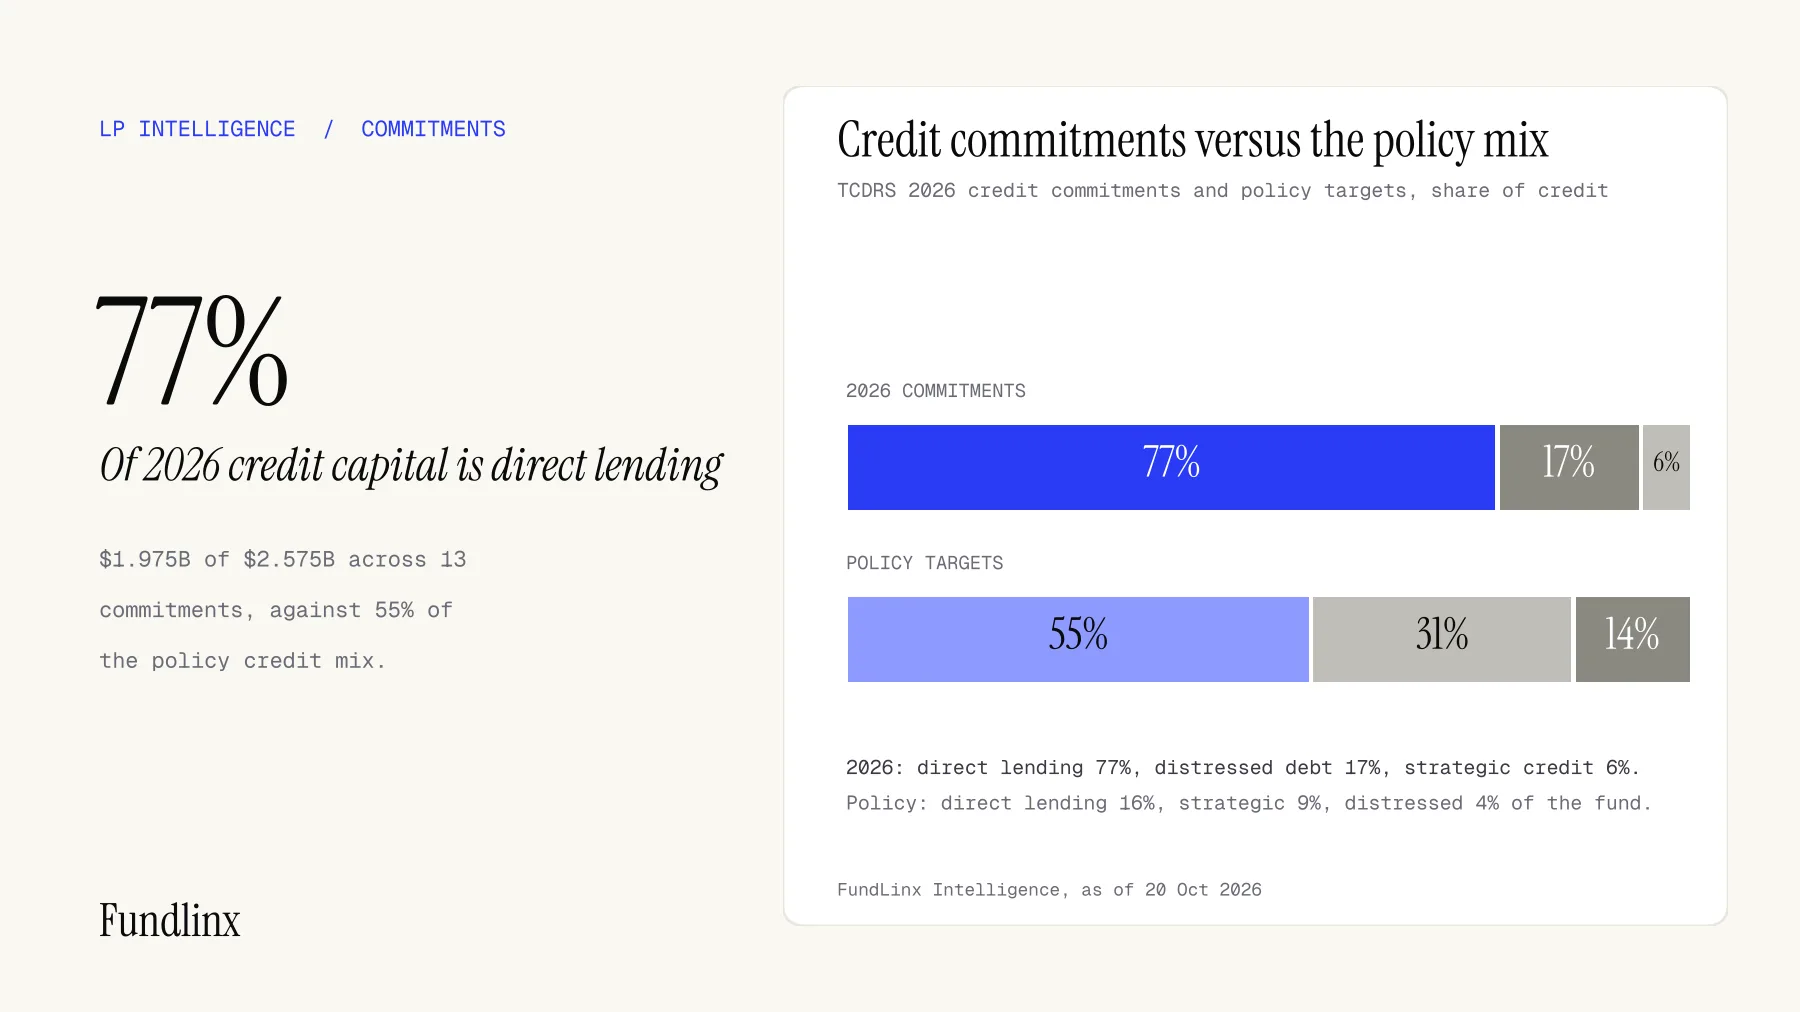
Across its three credit sleeves, TCDRS has committed about $2.6 billion in 13 commitments this year, our total of $2.575 billion. Direct lending is $1.975 billion, or 77% of the capital and 10 of 13 commitments (77%). Distressed debt is $450 million (17%) across two commitments (15%): $150 million to Ares Special Opportunities Fund III in January and $300 million to Silver Point Tactical Credit Opportunities Fund in June. Strategic credit is $150 million (6%) in one commitment (8%), to Highbridge Tactical Credit Fund in May.
Set that against the pension's policy targets of 16% direct lending, 9% strategic credit and 4% distressed debt, which add up to 29% for credit. Direct lending is 55% of that credit target but has taken 77% of the credit capital committed this year, while strategic credit is 31% of the target and has taken 6%. These are flows of new commitments, not holdings, and the shares are our arithmetic, but they show where the pension's pacing has been heaviest.
The private equity side
Over the same stretch, from 4 August to 30 September, TCDRS closed eight private equity commitments. Seven were in dollars and total $440 million, with tickets from $20 million to $110 million, and one was EUR 35 million to Aspira Fund I. They include $110 million to GTCR XV, $100 million to Spectrum Equity XI-A, $80 million to TCV Global Growth XIII, $50 million each to MED IV and AKKR Strategic Capital II, and $30 million and $20 million to two New Enterprise Associates 19 vehicles. The average dollar ticket is about $63 million, roughly a third of the direct lending average. Earlier in the year the pension committed $60 million to Aphias Capital Fund I, the debut fund we covered when it closed above $1.05 billion. We covered the manager behind the Spectrum ticket in our note on its Fund XI close.
The LP behind the ticket
TCDRS is a multi-employer public pension for Texas counties and districts and one of the more credit-heavy US pension funds. Its policy targets put 16% in direct lending, 9% in strategic credit, 4% in distressed debt and 25% in private equity. Inside private equity, the sub-targets are 50% buyout, 25% venture, 20% non-US and 5% real assets. It comes back to managers it knows: TPG has two of this year's direct lending commitments and Silver Point has one in direct lending and one in distressed debt.
What GPs should do now
This is our advice, not something the pension has said. Direct lending managers should plan for a ticket of $200 million to $300 million, a platform with a full-cycle track record and a clear answer on why a dedicated vehicle suits the pension. Two of the ten closings carry the "(TX)" suffix, so it is reasonable to ask in a first meeting whether a pension-specific vehicle is on the table.
Strategic credit looks like the lighter sleeve this year. A manager in high-yield, hybrid or opportunistic credit can use the pension's own numbers to explain why the sleeve has room. Private equity managers face a different size: tickets in the latest stretch were $20 million to $110 million, so a first-time or mid-sized fund is not priced out. Whatever the strategy, have an up-to-date diligence pack ready, as set out in our guide to the LP diligence pack, because the pension's closings arrive in clusters.
What to watch next
Watch for an eleventh direct lending closing before year end, a second strategic credit commitment, and the pension's 2027 pacing plan, which was reported in early January this year. FundLinx members can see which pensions are writing the largest credit tickets this quarter.
FundLinx Intelligence | FundLinx.ai
Playbooks, LP moves and compliance notes for emerging managers. Unsubscribe any time.