CPP Investments and Temasek Return to Nuveen's Australian Real Estate Debt Strategy as It Passes A$1 Billion at First Close
Two repeat LPs are back in Nuveen's new Australian property debt strategy, which opened above A$1 billion. CPP Investments committed A$300 million, the same cheque it wrote for the last one.
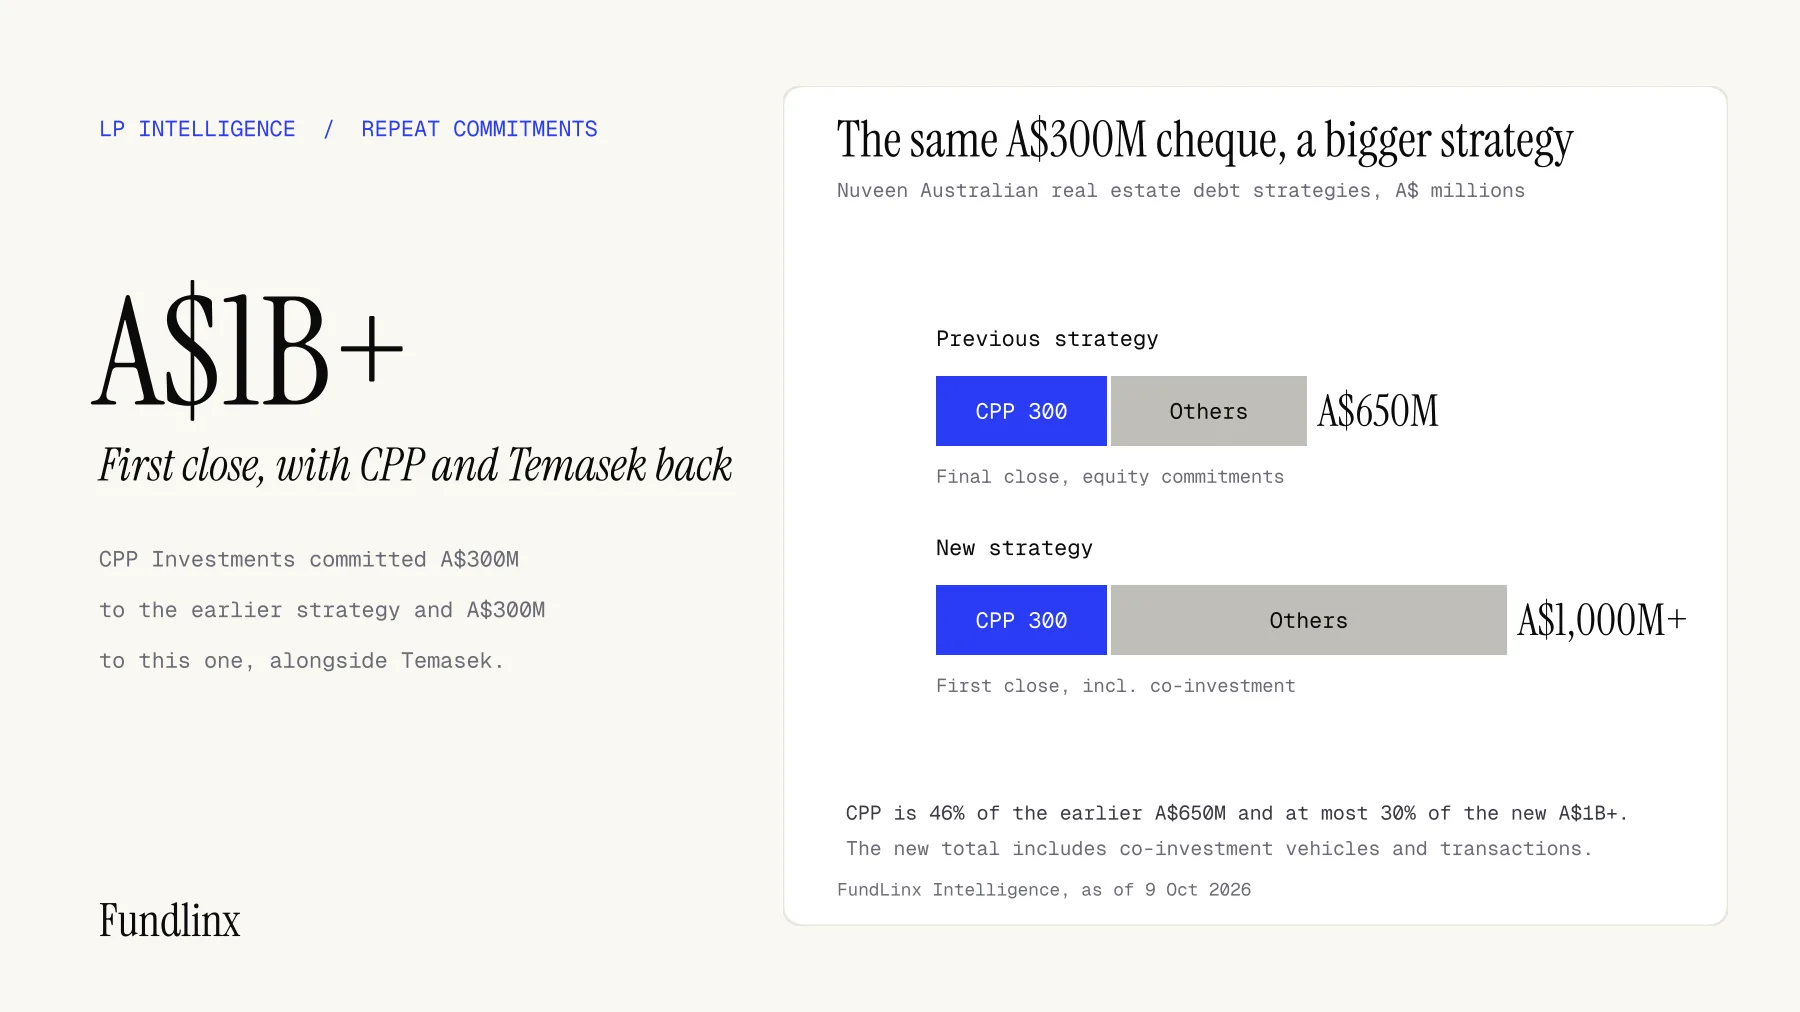
On 7 October 2026, Nuveen Real Estate announced that its new Australian commercial real estate debt strategy has secured more than A$1 billion at first close. The total includes co-investment vehicles and transactions, and the announcement gives no split between them, no target size and no fund name. What it does give is the investor line-up. CPP Investments committed A$300 million through its CPPIB Credit Investments Inc. subsidiary, Temasek came back with an amount it did not disclose, and TIAA, Nuveen's parent, invested alongside them. Both outside investors are re-investing after backing the previous strategy.
What was announced
The new strategy lends to repeat institutional borrowers against prime Australian property, using senior and junior loans with modest leverage and financial covenants. Nuveen named industrial, logistics and residential as preferred sectors and said it would be selective on alternatives, retail and office. The previous strategy closed with A$650 million of equity commitments, and the platform has committed about A$2 billion of gross loan investments across its funds and co-investment vehicles. Nuveen's global real estate debt platform manages about US$40 billion with 63 dedicated debt specialists. Temasek and Nuveen's private capital arm also announced a strategic partnership in September 2025, so this is the second visible step in that relationship. Dugald Marr, Nuveen Real Estate's Head of APAC Debt, said the re-investment reflects shared conviction in the strategy, and Raymond Chan, Managing Director and Head of APAC Credit at CPP Investments, described the commitment as a renewed endorsement of Nuveen's platform and track record.
How this compares with the previous strategy
CPP Investments committed A$300 million to the earlier strategy in 2025 and has now committed A$300 million to this one. That cheque was 46% of the earlier strategy's A$650 million of equity commitments and is at most 30% of the new A$1 billion plus, so CPP's share of the vehicle has fallen even though its cheque has not moved. The two totals are not like for like. The new figure includes co-investment vehicles and transactions, while the 2025 announcement said the earlier strategy's assets, including co-investment capital, were expected to exceed A$1 billion. On that basis the strategy has matched the earlier scale at first close rather than doubled it, and the fair reading is that demand held up. Of the three investors named, one disclosed an amount (33% by count), and that single amount accounts for at most 30% of the capital raised.
This is the fourth CPP Investments story we have covered since 1 October, after its stake in Prestige Hospitality Ventures, the sale of two Sydney toll road stakes and the AT&T fiber venture with GIP. Taken together they show a plan that is both selling mature Australian assets and re-upping with managers it already knows.
The LPs behind the cheques
CPP Investments reported net assets of C$863.6 billion at 30 June 2026, up from C$793.3 billion at the end of the prior quarter, after a 7.5% net return in the first quarter of its fiscal year. It is one of the largest public pension investors in the world and a regular lead investor in credit and real assets, which is why its A$300 million is the figure the market reads first. Temasek, the Singapore state investor, reported a net portfolio value of S$518 billion, about US$401 billion, at 31 March 2026, with a one-year shareholder return of 10.5% and a 20-year return of 6.8%. It said private credit is 2% of its portfolio with a goal of 5% by 2031, and that its Aranda Principal Strategies platform now manages more than S$13 billion. Neither LP's announcement suggests an appetite for first-time managers. The pattern here is an established platform with a proven first vintage, which is the profile both investors have rewarded. Both sit among the larger names on our lists of sovereign wealth investors.
What GPs should do now
This is advice, not something the announcement says. Real estate credit managers with Australian or Asia-Pacific exposure should treat the repeat commitments as a benchmark for what a second vintage has to prove. The most persuasive evidence is the re-up rate from your first-fund investors, the share of loans made to repeat borrowers, and loss and covenant data through the last rate cycle. A cheque of A$300 million is a large share of any vehicle under A$2 billion, so managers raising smaller funds should expect the large pensions to ask for a co-investment sleeve or a separate account rather than a straight fund commitment, which is how this deal reached its total. A first close usually means later closes are planned, though the announcement does not say when, so managers still raising in the same strategy should expect these LPs to benchmark them against this deal.
What to watch next
Watch for Temasek's amount if it is ever disclosed, for any announcement of a further close, and for CPP Investments' next quarterly update to see how its credit and real estate debt allocations moved. FundLinx members can see which LPs are re-upping with credit managers this quarter.
FundLinx Intelligence | FundLinx.ai
Playbooks, LP moves and compliance notes for emerging managers. Unsubscribe any time.