Pennsylvania SERS Commits Up to $130 Million to Reverence Capital Partners, Its First Deal With the Manager
Pennsylvania SERS will put up to $130 million into a manager it has never backed, split between a flagship fund and a sidecar, while its own figures show private equity 1.7 points under target.
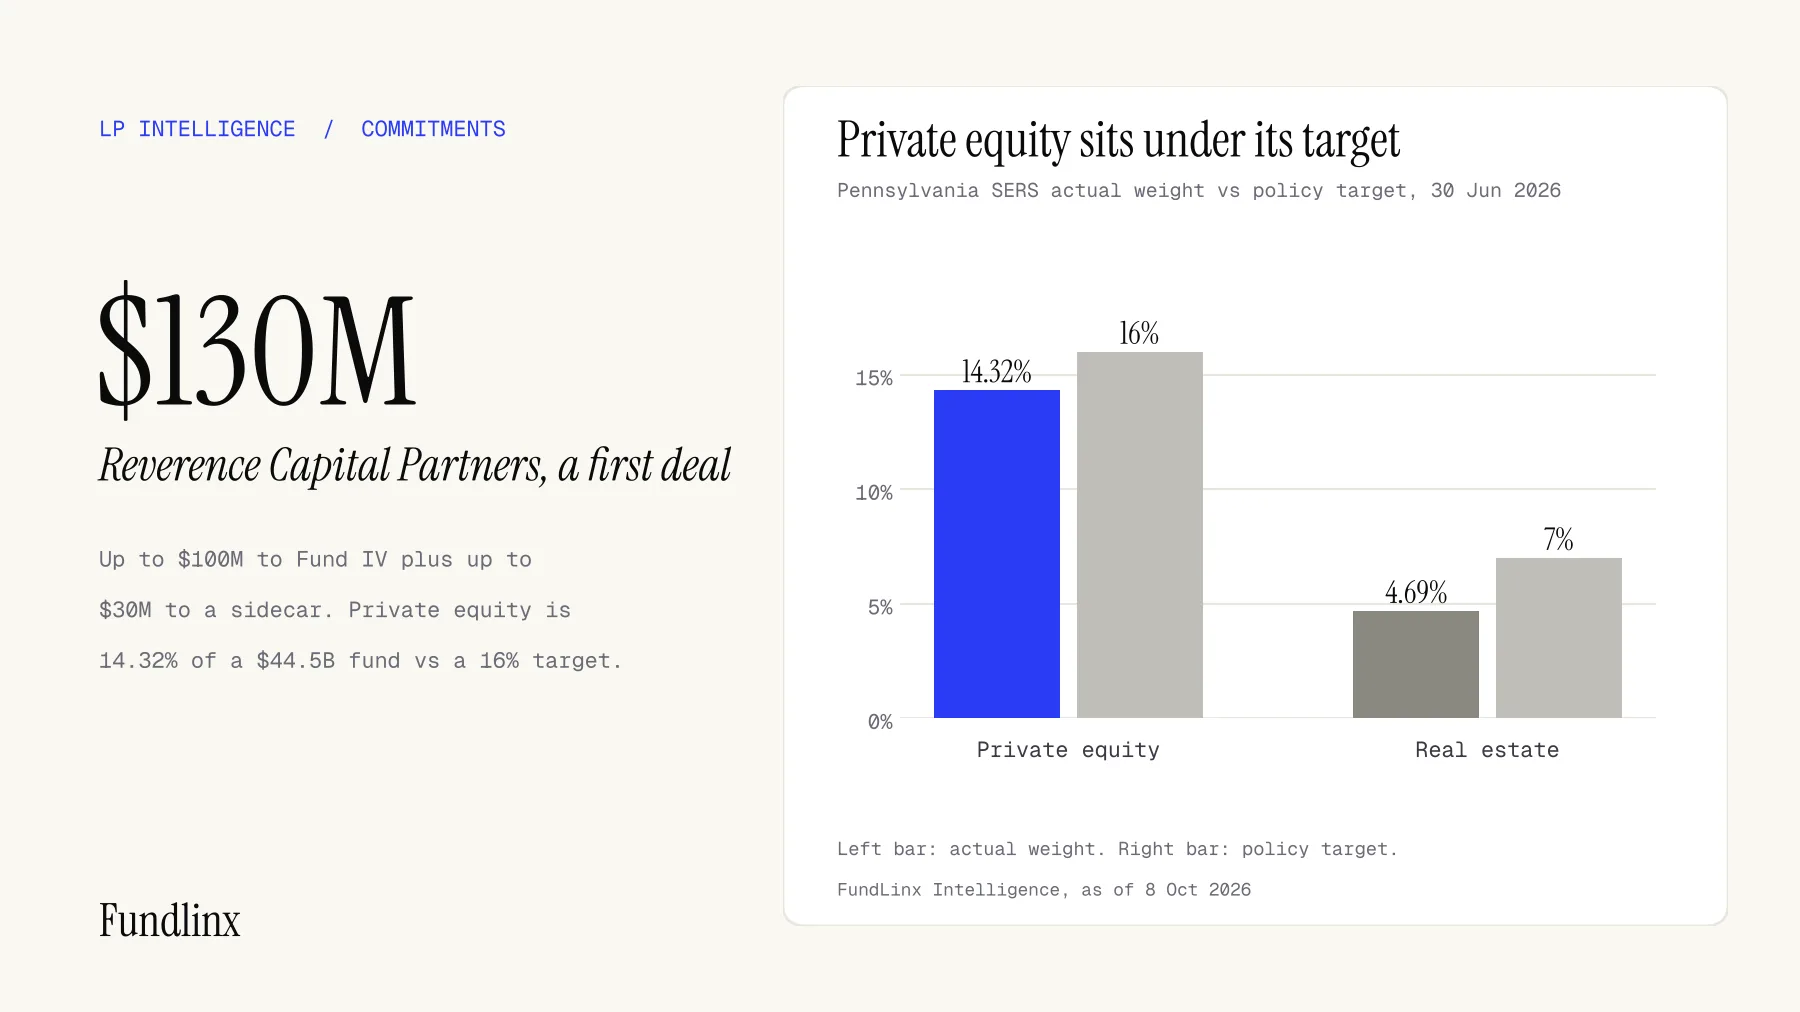
Pennsylvania SERS has committed up to $130 million to Reverence Capital Partners, a manager the plan had not backed before. The money is split between up to $100 million for Reverence Capital Partners Opportunities Fund IV and up to $30 million for a co-investment sidecar that invests alongside it. The retirement system's investment committee took up the item on 29 September 2026, and its full board took it up on 6 October 2026. The size of Fund IV was not disclosed.
Where the plan sits against its own targets
The plan's own figures for 30 June 2026 put total assets at $44.5 billion. Private equity was $6.37 billion, or 14.32% of the fund, against a policy target of 16%. Real estate was $2.09 billion, or 4.69%, against a target of 7%. On our arithmetic, a 16% weight would be about $7.12 billion, so private equity sits roughly $750 million under its target, and a 7% real estate weight would be about $3.11 billion, which leaves that sleeve about $1.03 billion under. Those are our calculations from the plan's own figures, not numbers the plan published.
The first half was uneven. In the first half of 2026 the total fund returned 6.35%, while private equity lost 0.69% and real estate lost 0.83%. In the second quarter alone the fund returned 7.84% and private equity fell 2.16%. In the first quarter, private equity returned 1.51% against 3.27% for its benchmark. The same sessions also covered asset allocation and rebalancing policy, so the Reverence commitment landed in the same sessions where the plan was reviewing how far each asset class had drifted.
How this compares with the plan's other 2026 private equity decisions
Reverence is the fourth private equity commitment we found among the plan's 2026 decisions. On 3 March the board approved up to $100 million to Francisco Partners VIII, $30 million to Francisco Partners Agility IV and $50 million to a co-investment vehicle. On 5 May it approved up to EUR 100 million, about $116 million, to PSG Europe III. On 16 June it approved up to $65 million to SkyKnight Capital Fund V and $35 million to a sidecar. Together with Reverence, those four decisions total about $526 million, using the plan's own dollar conversion for the euro commitment.
Sidecars and co-investment vehicles are a pattern. They account for about $115 million of that $526 million, or 21.9% of capital, and three of the four decisions, or 75% by count, include one. The Reverence sidecar is 23.1% of the $130 million. These percentages are our arithmetic and cover only the commitments named above, not every commitment the plan may have made this year. For a wider view of how public plans are deploying, see our note on how US public pensions committed $100.9 billion to private equity in 2025, and on a smaller commitment of the same kind, Sacramento County's $35 million buyout fund ticket.
The LP behind the ticket
Pennsylvania SERS is the retirement system for Pennsylvania state employees, a US state pension fund with $44.5 billion in assets. It meets in committee roughly a week before each board meeting. Its board has already shown this year that it backs managers it has not used before, since Reverence is a first relationship, and that it will write tickets of $65 million to about $116 million into a single fund. In real assets, Ohio PERS put $800 million into three real estate debt vehicles, which we covered in our note on its real estate debt allocation.
What GPs should do now
This section is our advice and not something the plan said. First, if you raise private equity funds in the $65 million to $116 million ticket range, treat Pennsylvania SERS as a live prospect. A first-time relationship got a full-sized ticket this month, so incumbency is not a requirement.
Second, put a co-investment offer in the first meeting. Three of the plan's four named 2026 decisions paired a fund with a sidecar or co-invest vehicle, so a pitch that already describes the sidecar terms and the allocation process will match how the plan appears to buy.
Third, lead with a clear track record and a view on the current marks. The plan is looking at private equity returns that trail the total fund, so an LP analyst will want to see how your realized and unrealized values hold up and how much of your portfolio sits in any sector that has been marked down.
Fourth, time the approach to the committee calendar. Committee meetings are held about a week before board meetings, so materials that reach staff after a committee date will most likely wait for the next cycle.
What to watch next
The plan's committees meet again on 1 December and its board on 8 December 2026. Watch for the board resolution on Reverence, which should confirm the exact amounts and structure, for any change to the private equity and real estate targets that comes out of the allocation and rebalancing discussions, and for the third-quarter performance report, which will show how far private equity has moved against its target. FundLinx members can see which pension funds are adding to private equity.
FundLinx Intelligence | FundLinx.ai
Playbooks, LP moves and compliance notes for emerging managers. Unsubscribe any time.