Norway's Wealth Fund Loses 0.5% in the Third Quarter as Bonds Fall 3.5%, While Its Unlisted Renewable Infrastructure Returns 7.5%
Norway's wealth fund returned -0.5% in Q3 2026 as bonds fell 3.5%, while its unlisted renewable energy infrastructure returned 7.5% and a stronger krone cut NOK 472 billion from value.
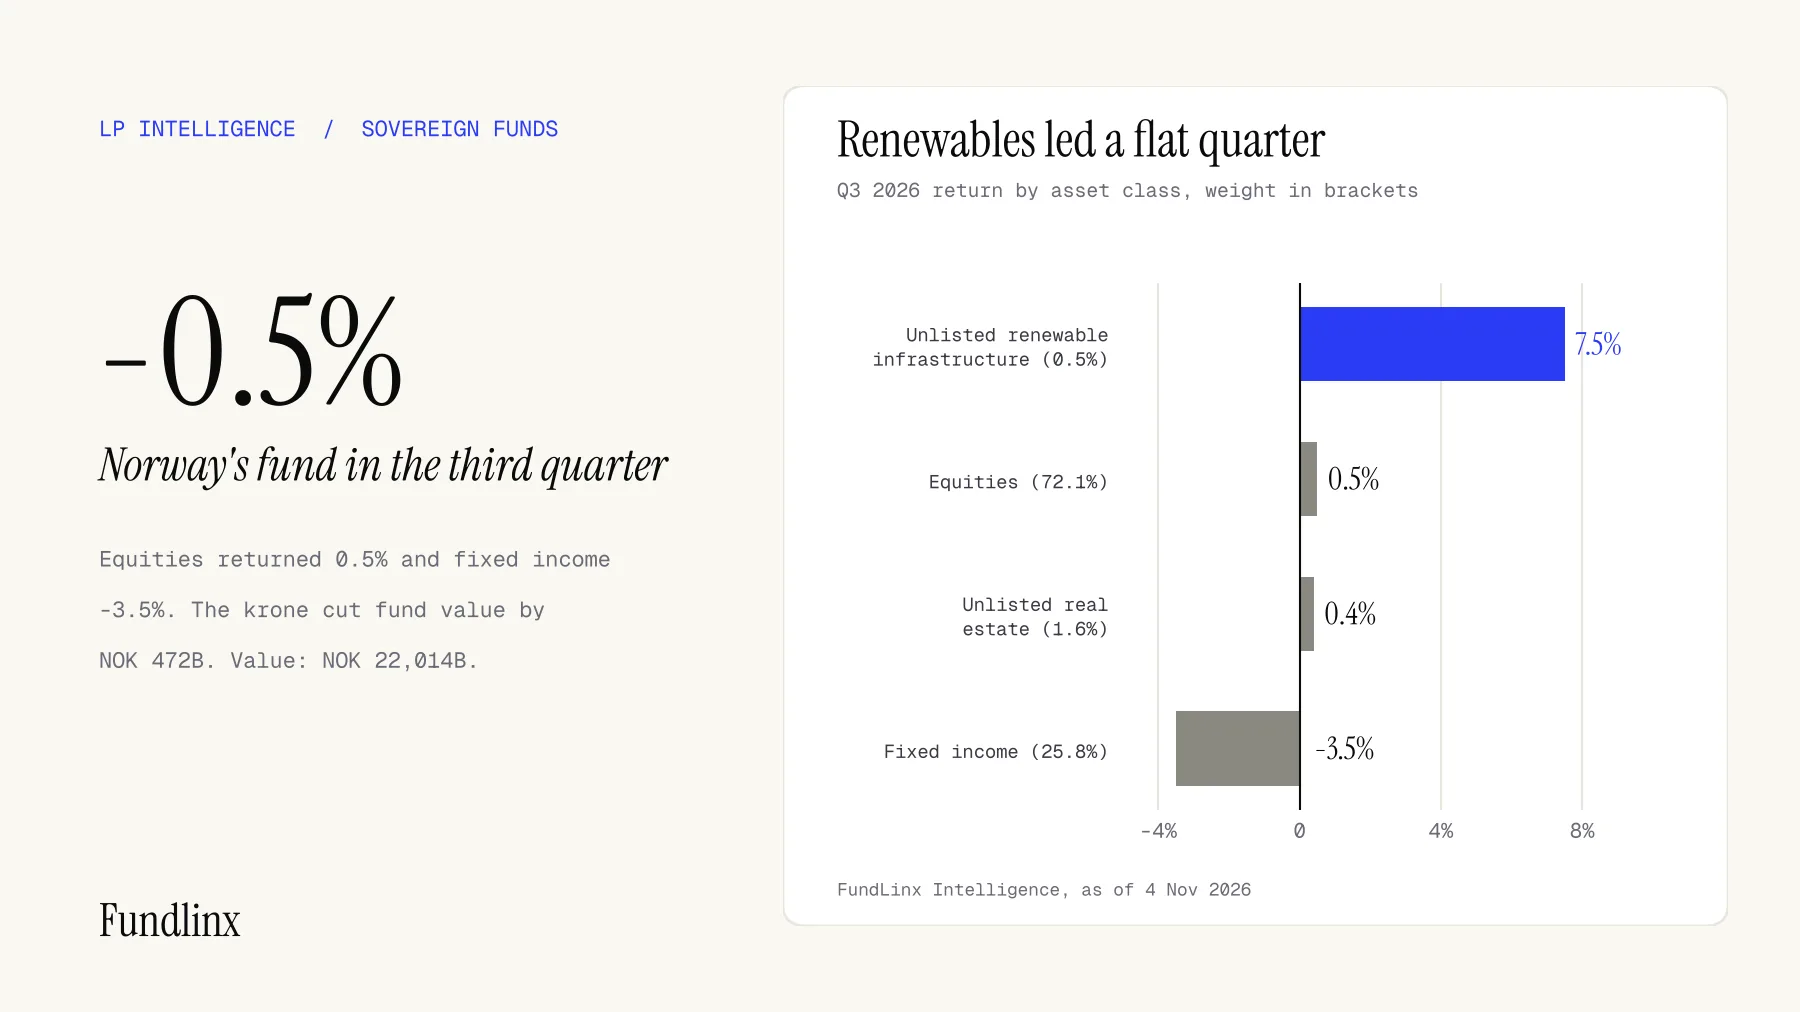
Norway's wealth fund reported on 22 October 2026 that it returned -0.5% in the third quarter, with bonds down 3.5% and a stronger krone taking more off its reported value than the markets did. The fund holds Norway's sovereign wealth savings and ended September at NOK 22,014 billion. It also reported that its small unlisted renewable energy infrastructure holding returned 7.5%. For a GP, the headline is the loss, but the detail worth keeping is how little of the fund sits in unlisted assets and how those assets behaved while the rest of the portfolio stood still.
What was announced
The fund said its return for July to September 2026 was -0.5%, which was 0.18 percentage points below its benchmark. The accounting loss was NOK 278 billion, roughly 26 billion euros or 31 billion US dollars at recent exchange rates. A stronger krone reduced the value of the fund's foreign holdings by a further NOK 472 billion, and net inflows after management costs added NOK 80 billion. Together these took the fund's value down by NOK 670 billion over the quarter, to NOK 22,014 billion at 30 September 2026. The announcement gave returns for four asset classes: equities 0.5%, fixed income -3.5%, unlisted real estate 0.4% and unlisted renewable energy infrastructure 7.5%.
The numbers
Putting the quarter in proportion takes a little arithmetic of our own. Adding the NOK 670 billion fall to the end-of-quarter value gives a starting value of NOK 22,684 billion for 1 July, so the fall was about 3.0% of starting value. The currency effect alone was about 2.1% of starting value, and net inflows were about 0.35%. At 30 September, equities were 72.1% of the fund, fixed income 25.8%, unlisted real estate 1.6% and unlisted renewable energy infrastructure 0.5%. Three of the four asset classes, 75% by count and 74.2% of the fund by value, had positive returns. The one negative class, fixed income, was 25.8% of the fund by value. The two unlisted classes together were about 2.1% of the fund, which is roughly NOK 460 billion on the end-of-quarter value. The 7.5% return came from the smallest holding, and the fund's own announcement does not say what drove it, so we do not offer a reason.
How it compares
A quarter this size gives little to compare with directly, because the fund reports against its own benchmark and we have not verified its earlier quarters. A different measure from a different group is the US public pension plans, whose 100 largest lost 1.4% in September alone, as we set out in our report on US public pension funded ratios. That is a one-month figure against a three-month one, so treat it as context, not a ranking. On the fund's unlisted activity, our earlier coverage covered a commitment to the sixth fund of an infrastructure manager that was 33% larger than its previous one and a European logistics partnership where it holds 96%. We read both as signs of a fund that builds its unlisted exposure through a small number of large partnerships.
The named LP
The Government Pension Fund Global is a sovereign wealth fund managed on behalf of Norway, and its profile sits among sovereign wealth funds and European LPs on FundLinx. Its quarterly figures give a value of NOK 22,014 billion and the four asset-class weights above. Its unlisted exposure in these figures is limited to real estate and renewable energy infrastructure, and the announcement gives no private equity allocation, no typical ticket and no record of backing first-time funds. We therefore offer no Fund I or Fund II view.
What a GP should do
This section is our advice, not guidance from the fund. First, do not read a -0.5% quarter as a pullback. Nothing in the announcement changes its unlisted plans, and the loss came from bonds and the currency. Second, pitch to the size of the sleeve. With about 2.1% of the fund in unlisted assets, a strategy has to fit real estate or renewable energy infrastructure to be relevant, and it helps to say so in the first line. Third, report against a benchmark. The fund itself states its return against one, so a manager who does the same will read as familiar. Fourth, show currency in plain terms: a quarter in which exchange rates moved more than markets will make any reader of your track record ask how much of your return was currency. Fifth, size your ask honestly, keeping your own fund size and a realistic share of it in view.
What to watch next
Watch the fund's next quarterly result for any change in the unlisted weights, and for whether renewable energy infrastructure holds its lead. If you are building a list of sovereign LPs, FundLinx members can see which institutions are allocating in your strategy.
FundLinx Intelligence | FundLinx.ai
Playbooks, LP moves and compliance notes for emerging managers. Unsubscribe any time.