AustralianSuper Has Committed More Than A$1.5 Billion to Australian Venture, Up From About A$600 Million
AustralianSuper says its Australian venture commitments have passed A$1.5 billion, still under 0.5% of a portfolio above A$430 billion. It invests through several managers plus some co-investment.
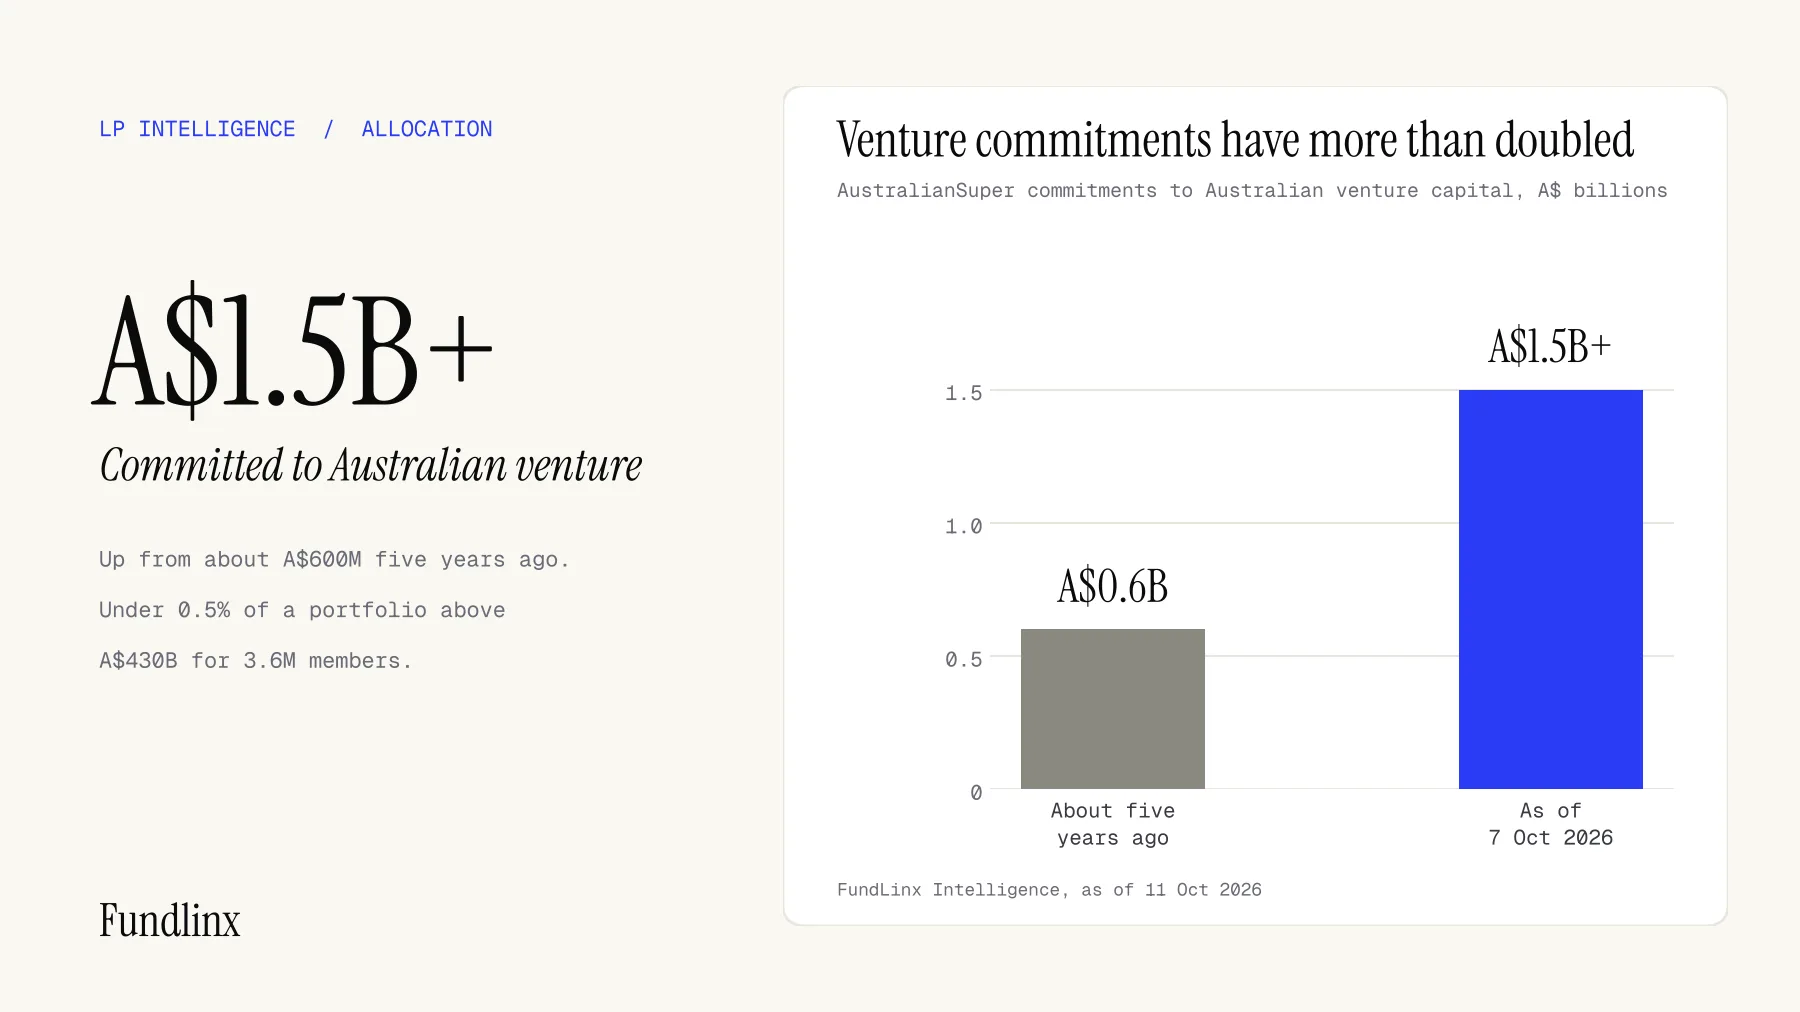
On 7 October 2026, AustralianSuper published a long account of its Australian venture capital programme, in the form of a Q&A with Lilian Fang, its Head of Private Equity for Asia Pacific. The headline figure is that the fund has committed more than A$1.5 billion to Australian venture, up from around A$600 million five years ago. That is a rise of about A$900 million, or roughly 2.5 times, and it still represents less than 0.5% of a portfolio above A$430 billion. The article gives its figures in dollars, which we read as Australian dollars. For GPs, the value is in what a very large pension fund says about how it builds a small, growing sleeve.
What AustralianSuper published
The fund said it manages more than A$430 billion for 3.6 million members as at 30 June 2026. Through its venture managers it has invested in more than 250 Australian start-ups since 2016, and it is invested in seven of the nine Australian unicorns. Named managers were Blackbird, Square Peg and AirTree Ventures. The fund said it diversifies across several managers, adds selective co-investment alongside them, and spreads exposure across companies, sectors, stages and vintages instead of trying to time the cycle. It said its venture portfolio has outperformed the S&P/ASX 300 Accumulation Index by a comfortable margin over the long term, while cautioning that the portfolio is young and that short-term results should not carry much weight. The performance claim rests on the fund's own portfolio data as at 30 June 2026 and we have not been able to check it independently.
How the numbers compare
By our arithmetic, A$1.5 billion is about 0.35% of A$430 billion, which is consistent with the fund's own "less than 0.5%" and leaves room to grow before it reaches that ceiling. At 0.5% the sleeve would be about A$2.15 billion, so the stated ceiling is about A$650 million above today's commitments. The fund's market data also puts Australia's venture-backed ecosystem value up 13.7 times between 2016 and May 2026, against 11.2 times in the US and 6.9 times in the UK, and AI's share of investment at 23%, up from 7% in the 2020 to 2022 boom. The same article says 41% of early-stage venture funding since 2024 came from offshore investors, against 21% in Europe and the US. This is the third venture-focused LP story we have covered since 29 September, after OMERS Ventures naming a new head and ABP's EUR 250 million commitment to EQT's Scaleup Europe fund.
The LP behind the commitments
AustralianSuper is Australia's largest superannuation fund, by the statistics it cites for June 2026. It is a long-term investor and said that higher interest rates have not led it to cut venture exposure automatically, with its pace of investment staying responsive to valuations, financing conditions and the quality of opportunities. On policy, it supports in broad terms a proposed concession that would keep a 50% capital gains tax discount for eligible investments in qualifying start-ups, and it said it has engaged with the Government on the design. On the superannuation performance test, it supports a well-designed benchmark for emerging assets and said the test is not a material constraint on its venture portfolio. On concentration, the fund said the test is whether the portfolio as a whole delivers an appropriate long-term outcome for members after risk and costs, and it answered "an unequivocal yes". It also said private markets let it invest before companies list, and that managing liquidity matters more as holding periods lengthen. The practical effect for GPs is that the fund describes itself as a patient, diversified buyer, not a fast-moving one. By our reading, a venture sleeve under 0.5% is small for the fund but large for most venture managers, because a single commitment from a fund of this size can be a meaningful share of a venture fund. You can find similar institutions on our list of pension fund LPs.
What GPs should do now
This section is our advice, not something the fund said. A sleeve of this size, built across several managers, suggests the fund is more likely to add a complementary manager than to replace one, so the strongest pitch explains what your fund adds to a portfolio that already holds well-known names. The fund also said it uses selective co-investment, so offering a co-investment sleeve gives it a way to add exposure without enlarging a fund commitment. Liquidity matters too: the article says secondary markets can provide some liquidity as holding periods lengthen, so a clear view on how you handle secondaries and long holds belongs in your materials. We cover the selection criteria it published in our companion outreach guide for venture managers.
What to watch next
Watch for the next time the fund updates its venture commitment figure, for the outcome of the proposed tax concession, and for the Treasury process on benchmarks for emerging and alternative assets, which included a consultation in May 2026. FundLinx members can see which large pensions are adding managers in your strategy.
FundLinx Intelligence | FundLinx.ai
Playbooks, LP moves and compliance notes for emerging managers. Unsubscribe any time.