A Pension's Real Estate Manager Opened a US Office Account on 23 October: How to Write Outreach to an LP That Invests Through a Manager
Bouwinvest, which serves more than 35 institutional clients, launched a US office account with Tishman Speyer on 23 October. How to write to an LP that invests through a manager, not directly.
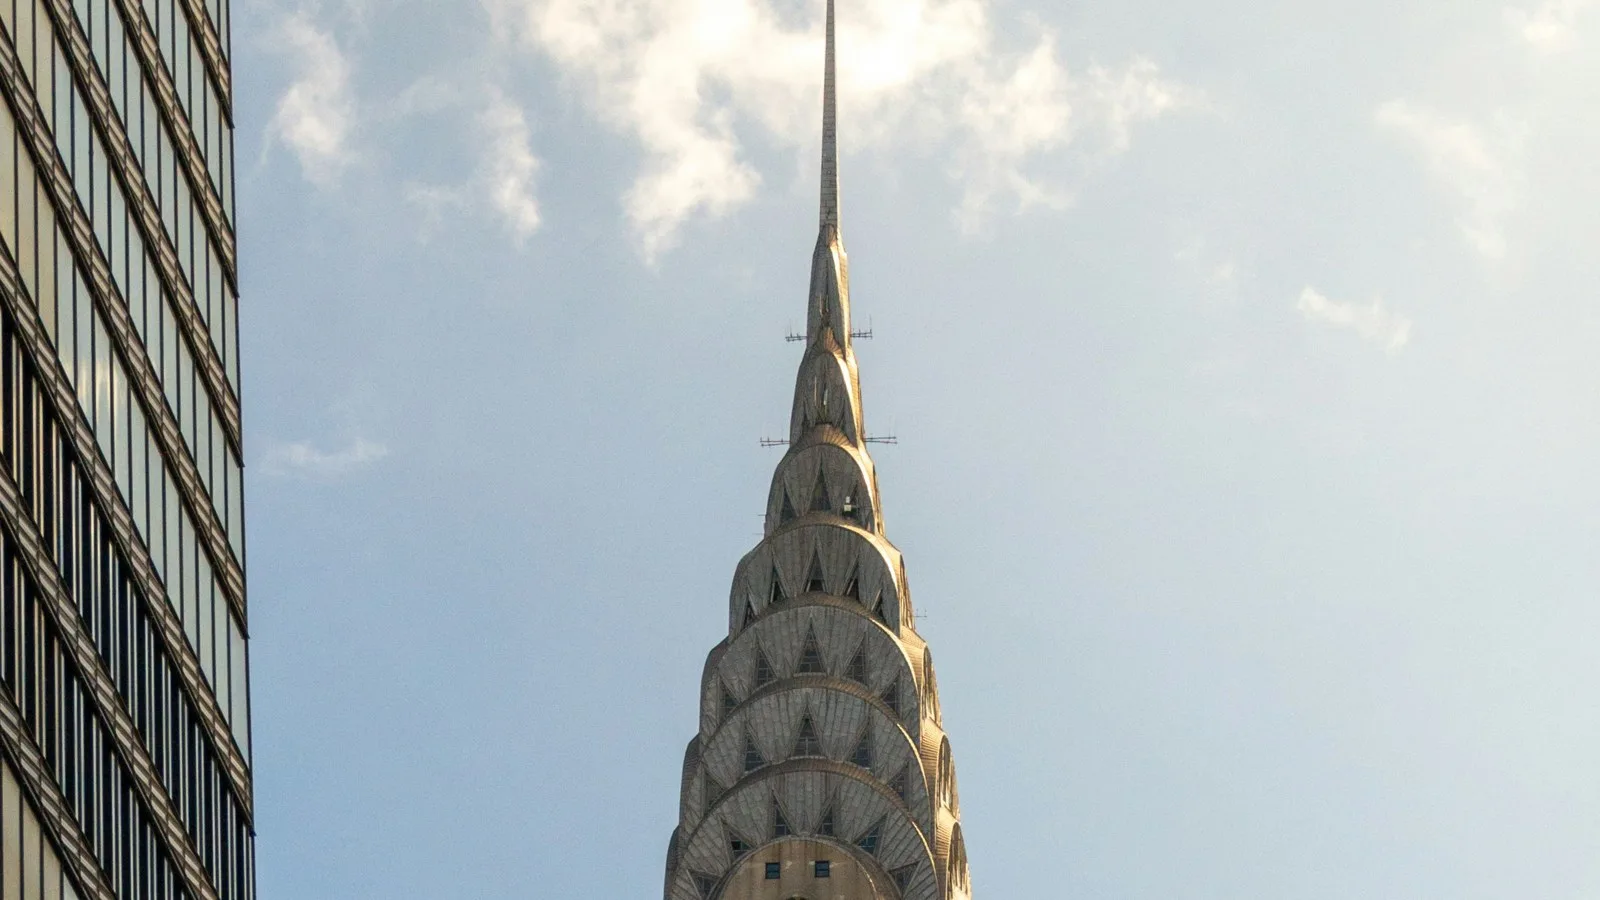
Bouwinvest Real Estate Investors and Tishman Speyer launched a separately managed account on 23 October 2026 to buy top-tier US office buildings, with the Chrysler Building's ground lease as the first investment. Coverage of the launch says Bouwinvest serves more than 35 institutional clients, and that bpfBOUW is its largest client and a shareholder. That is the useful detail for outreach: when an investor like Bouwinvest writes the cheque, the person who decides, the person who is consulted and the institution whose money it is can be three different parties. Our news analysis of the launch has the deal facts. This piece is about the message. The steps below are our advice, not guidance from Bouwinvest.
Why the usual LP email misfires
Most outreach assumes one reader, a chief investment officer or a head of a strategy, who can say yes or no. An LP that invests through a manager breaks that. The manager's team picks the partner, the manager's clients may have a say in what is bought, and the manager may be judged on how well it chose specialists. In this launch, a Bouwinvest director described investing selectively, early in the cycle and through specialist partners. If your email reads like a fund pitch to a pension, it answers the wrong question. The manager wants to know why you are the specialist for a given market and what you would do for a single client.
Find the right first reader
Work out who at the manager covers your strategy and region. In this case the person quoted leads North American investments, which is the kind of title to look for. Use public materials only: the announcement, the manager's own pages and conference programmes. Do not guess at personal contact details, and do not write to the end investor when the manager runs the mandate, as it can look like going around the manager. If you want the end investor to hear about you, the better route is a warm introduction through someone who already works with both, and our guide to warm paths shows how to map one.
What the first message should contain
Keep it short and specific, and write it as advice to a peer on a decision they are already making. Lead with the hook that is public and dated, for example that you saw the 23 October launch of the US office account and its first investment. State your specialism in one sentence, with the market, the asset type and the strategy, core-plus or value-add. Give one proof point that is verifiable, such as a realised deal or a repeat relationship, and avoid projected returns in a cold message. Then offer a form the manager can use: a deal-by-deal co-investment option or a view on how a one-client account with you would work. End with one low-effort ask, such as a 20-minute call, and say what you will send beforehand.
What to leave out
Leave out any claim about the account's size, because none was disclosed. Do not name the other institutional investors in the Chrysler deal; they were not named. Do not cite a ticket size for Bouwinvest or PSP. Do not tell the manager the office market is recovering unless you can show it in your own deals. For a related example of tailoring outreach to how an LP measures managers, see our note on writing to an LP that tracks a passive benchmark.
Subject line and length
Keep the subject line plain and tied to the public event, for example a reference to the new US office account and your market, not a headline about your fund. Aim for roughly 120 words, which is enough for the hook, the specialism, one proof point and the ask. Attach nothing on a first message. If the manager wants a deck, a short reply will say so, and a two-line summary in the body does more work than a 30-page file the reader has not asked for. Write in the manager's terms: they described their approach as selective and early in the cycle, so a message that says what you would pass on will land better than one that lists everything you could buy.
If you already know someone there
If a colleague, co-investor or adviser already works with the manager, ask them for a view on timing before you write, not an introduction straight away. A short note from them saying the manager is open to specialist partners in your market is worth more than a polished email. Offer to send them a three-line summary they can forward unchanged, so the introduction costs them nothing, and thank them whatever the outcome.
A second message, a week later
If there is no reply, send one follow-up that adds something new, not a nudge. A recent leasing result, a new asset under offer in a named market or a one-page description of a single-client account is enough. Then stop. The manager may be working through a first acquisition, and a quiet period is normal.
What to watch next
Watch for further acquisitions under the account and for any disclosure of its size, either of which would tell you whether the manager is building a programme or doing a single deal. FundLinx members can see which institutions are active in your strategy.
FundLinx Intelligence | FundLinx.ai
Playbooks, LP moves and compliance notes for emerging managers. Unsubscribe any time.